
Pause. Review. Realign. Begin again.
Half the year is already behind you.
Which means this is the perfect moment to pause.
Not because you’ve done anything wrong.
Not because your budget needs to be “fixed.”
And definitely not because you need to start over.
But because your financial life deserves a check-in.
The beginning of the year often comes with ambitious goals.
Save more.
Spend less.
Pay off debt.
Get organised.
Finally get serious about your finances.
Then life happens.
Unexpected expenses appear.
Plans change.
Income shifts.
Goals evolve.
And somewhere between January and now, the financial plan you started with may no longer look quite right.
That’s okay.
You don’t need a new year to change your financial direction.
You simply need a moment to pause, look at what’s happening and decide what comes next.
Welcome to The Mid-Year Money Reset.
A little less pressure.
A little more clarity.
A chance to reconnect with your money and make the next six months count.
What is a mid-year money reset?
A mid-year money reset is a financial check-in designed to help you review the first half of the year and intentionally plan for the months ahead.
Think of it as a halfway point between your annual financial review and your weekly money routine.
It’s your opportunity to ask:
Where am I now?
What’s working?
What’s changed?
What needs my attention?
What still matters?
What do I want the rest of the year to look like?
You can review:
- Your income
- Your spending
- Your budget
- Your savings
- Your debt
- Your financial goals
- Your bills
- Your subscriptions
- Your emergency fund
- Your upcoming expenses
- Your financial habits
- Your lifestyle
- Your longer-term plans
The purpose isn’t to create more financial rules.
It’s to create more financial awareness.
You don't need to start over.
This is important.
If your finances don’t look exactly how you imagined they would in January, resist the urge to throw everything away and start again.
Maybe you didn’t save as much as planned.
Maybe you spent more.
Maybe you had an unexpected expense.
Maybe your income changed.
Maybe your priorities shifted.
Maybe you simply lost momentum.
None of that means you’ve failed.
It means life happened.
A financial strategy should have room for real life.
So instead of asking:
“Why didn’t I stick to my plan?”
Try asking:
“What can I learn from the last six months?”
That question changes everything.
Because the goal of a reset isn’t punishment.
It’s information.
THE MID-YEAR MONEY RESET
PAUSE → REVIEW → REALIGN → RESET → MOVE FORWARD
Your mid-year reset can be beautifully simple.
PAUSE
Step away from the noise.
REVIEW
Look honestly at your numbers and your habits.
REALIGN
Reconnect your money with your current priorities.
RESET
Make the changes that actually matter.
MOVE FORWARD
Create a simple plan for the next six months.
That’s it.
No dramatic financial overhaul required.
01 - PAUSE
Before you touch the numbers, check in with yourself.
Financial organisation starts with awareness.
So before opening your banking app or spreadsheet, take a moment to think about the first half of your year.
Ask yourself:
How has life changed since January?
What has gone well?
What has been harder than expected?
What financial decision am I proud of?
What has surprised me?
What has become more important?
What no longer matters as much?
What do I want more of for the rest of the year?
Don’t rush to fix anything.
Just notice.
This is your opportunity to step out of autopilot.
02 - KNOW YOUR NUMBERS
Let’s get clear.
Now it’s time to look at the numbers.
Your budget is not a judgement.
It’s a snapshot.
And the clearer the snapshot, the easier it becomes to make decisions.
Write down your current:
Income
Essential expenses
Lifestyle spending
Savings
Debt
Investments
Emergency savings
Net worth
You can also compare your current position with where you were at the beginning of the year.
What changed?
That question is more valuable than simply asking whether the numbers are “good” or “bad.”
03 - REVIEW YOUR SPENDING
Where has your money actually been going?
Your budget tells you what you intended to spend.
Your transactions tell you what actually happened.
Take a look at the last few months and review your spending patterns.
Look for:
- Your biggest spending categories
- Recurring expenses
- Subscriptions
- Annual or quarterly bills
- Convenience spending
- Lifestyle spending
- Unexpected expenses
- Impulse purchases
- Expenses that increased
- Expenses that disappeared
Don’t look for reasons to feel guilty.
Look for patterns.
What keeps appearing?
What surprised you?
What genuinely added value to your life?
What no longer feels worth it?
Tracking spending can help reveal patterns that aren’t obvious when you’re only looking at individual purchases.
And sometimes the most valuable discovery isn’t where you can spend less.
It’s where you can spend better.
04 - FIND YOUR MONEY LEAKS
Give your finances a little edit.
Not every expense needs to be eliminated.
But every recurring expense deserves to earn its place.
Look through your:
- Subscriptions
- Memberships
- Apps
- Streaming services
- Phone plans
- Internet
- Insurance
- Bank fees
- Recurring deliveries
- Convenience services
Then ask:
Do I still use this?
Do I still need this?
Is it still good value?
Would I choose it again today?
If the answer is no, let it go.
If the answer is yes, keep it.
Intentional money management isn’t about cutting everything you enjoy.
It’s about knowing what deserves your money.
05 - CHECK YOUR BUDGET
Does your budget still fit your life?
This is where many people make a mistake.
They continue following a budget created six months ago even though their life has changed.
Your income may be different.
Your rent or mortgage may have changed.
Groceries may cost more.
Your priorities may have shifted.
You may have new subscriptions.
You may be travelling.
You may have a new financial goal.
Your budget should reflect your life now.
Go through each major category.
KEEP
What is working?
CHANGE
What needs adjusting?
REMOVE
What no longer belongs?
ADD
What is missing?
A budget should be a living system, something you adjust as your circumstances change rather than something you create once and forget.
06 - REVIEW YOUR SAVINGS
How is your future self doing?
Take a look at your savings.
Compare your current balance with where you started the year.
Then look beyond the number.
Ask:
What was I saving for?
Did I reach any of my goals?
Did my goals change?
Did I have to use my savings?
Am I saving consistently?
Does my current savings strategy still make sense?
If you’ve fallen behind, don’t panic.
Instead, calculate what would realistically be required for the remainder of the year.
For example:
If your goal was to save $6,000 over the year but you’ve saved $2,000 so far, you have $4,000 remaining.
Rather than thinking:
“I’m behind.”
Think:
“What strategy would make the remaining $4,000 achievable?”
You might adjust your timeline, contribution amount or priority.
The goal is to create a plan that fits reality.
07 - CHECK YOUR EMERGENCY FUND
Give yourself a little breathing room.
Your emergency savings are designed for unexpected financial situations.
During your mid-year reset, ask:
Has my cost of living changed?
Has my income changed?
Has my financial situation changed?
Would my current emergency savings provide enough breathing room for my circumstances?
There isn’t one perfect emergency fund number for everyone.
The right target depends on your circumstances, expenses, income stability and financial responsibilities.
What matters is having a financial buffer that you’re intentionally building towards.
And if you’re starting from a small amount?
That’s still a start.
Financial security is built gradually.
08 - REVIEW YOUR DEBT
Look at the progress, not just the balance.
Debt can feel emotionally heavy.
That’s why this part of your reset deserves a calm approach.
Write down your current balances.
Then compare them with the beginning of the year.
Ask:
Has my debt decreased?
Have my repayments changed?
Am I paying more interest than I expected?
Have I taken on any new debt?
What debt strategy makes sense for the next six months?
You don’t need to solve everything today.
Choose the next meaningful step.
Perhaps that’s:
- Making additional repayments where appropriate
- Reducing new debt
- Reviewing your repayment strategy
- Creating a debt payoff target
- Building a small financial buffer
- Seeking professional support if debt has become difficult to manage
Progress doesn’t have to be dramatic to be real.
09 - REVIEW YOUR FINANCIAL GOALS
Do your goals still feel like yours?
This might be the most important part of the reset.
Look at the goals you created in January.
Now ask:
Do I still want this?
Maybe the answer is yes.
Maybe the goal has changed.
Maybe you’ve already achieved it.
Maybe something more important has come along.
That’s why financial goals should be reviewed rather than blindly followed.
Create three lists:
KEEP
Goals that still matter.
CHANGE
Goals that need a new amount, timeline or strategy.
RELEASE
Goals that no longer reflect your life.
There is freedom in allowing your financial strategy to evolve.
10 - CHOOSE YOUR TOP THREE
You don’t need twenty goals.
Choose three priorities for the next six months.
For example:
01 – BUILD
Save $3,000 towards an emergency fund.
02 – REDUCE
Pay an additional $150 per month towards debt.
03 – ENJOY
Save $2,000 towards a holiday.
Your priorities can be completely different.
Maybe yours are:
Home
Travel
Debt
Savings
Investing
Business
Family
Education
Security
Freedom
The important thing is that they reflect your life.
11 - LOOK AT THE NEXT SIX MONTHS
What’s coming?
One of the easiest ways to feel financially overwhelmed is to only plan for today.
Look ahead.
Open your calendar.
What expenses are coming?
Think about:
- Birthdays
- Holidays
- Christmas
- Insurance renewals
- Car registration
- School expenses
- Medical costs
- Home maintenance
- Annual subscriptions
- Travel
- Weddings
- Major purchases
- Tax obligations
- Other known annual expenses
Now ask:
What can I prepare for now?
Known future expenses don’t need to become financial surprises.
Give them a place in your plan.
12 - CREATE YOUR SIX-MONTH MONEY MAP
Give the rest of the year direction.
Take your three financial priorities and turn them into a simple six-month roadmap.
MONTH 1
What needs to happen first?
________________________________
MONTH 2
What should I focus on next?
________________________________
MONTH 3
What progress should I review?
________________________________
MONTH 4
What needs adjusting?
________________________________
MONTH 5
What goal needs attention?
________________________________
MONTH 6
What do I want to have achieved?
________________________________
You don’t need to plan every financial decision.
You simply need a clear direction.
13 - RESET YOUR MONEY ROUTINES
Make financial organisation easier.
Ask yourself:
What financial task am I still doing manually that could be automated?
Perhaps you can automate:
- Savings transfers
- Bill payments
- Regular investments where appropriate
- Transfers between accounts
- Debt repayments
Automation can reduce the number of financial decisions you need to make throughout the month. Regular transfers and separate savings accounts can also make savings easier to maintain.
Your financial system should work quietly in the background.
You decide once.
Your system keeps going.
14 - CREATE YOUR “MORE OF THIS / LESS OF THAT” LIST
This is where your financial reset becomes personal.
MORE OF THIS
More intentional spending.
More saving.
More planning.
More financial organisation.
More experiences.
More financial confidence.
More preparation.
More freedom.
More conversations about money.
LESS OF THAT
Less impulse spending.
Less comparison.
Less financial avoidance.
Less forgotten subscriptions.
Less unnecessary clutter.
Less spending out of boredom.
Less guilt.
Less reacting.
Less “I’ll deal with it later.”
Your list becomes a simple financial philosophy for the second half of the year.
15 - GIVE YOUR MONEY A JOB
LIVE. ENJOY. PROTECT. PLAN. BUILD.
At Finance Strategy Co., we believe money works best when it has direction.
Think about your money in five ways.
LIVE
The money that supports everyday life.
Bills.
Groceries.
Transport.
Home.
Essentials.
ENJOY
The money that allows you to experience your life.
Travel.
Dining.
Hobbies.
Entertainment.
Experiences.
PROTECT
The money that creates financial breathing room.
Emergency savings.
Buffers.
Financial protection.
PLAN
The money preparing for what’s ahead.
Sinking funds.
Upcoming expenses.
Goals.
Larger purchases.
BUILD
The money supporting your longer-term financial future.
Savings.
Debt reduction.
Investments.
Wealth-building goals.
The exact structure will look different for everyone.
But the philosophy remains:
Your money should have purpose.
16 - CHECK YOUR FINANCIAL SYSTEM
Is your system helping or complicating your life?
Your mid-year reset is the perfect time to simplify.
Review:
☐ Bank accounts
☐ Budget
☐ Savings accounts
☐ Bills
☐ Subscriptions
☐ Expense tracking
☐ Savings goals
☐ Debt tracking
☐ Financial documents
☐ Automatic transfers
Then ask:
What can I simplify?
Maybe you have too many accounts.
Too many categories.
Too many subscriptions.
Too many spreadsheets.
Too many financial tasks.
Financial organisation doesn’t mean creating more work.
It means creating a system that makes your money easier to manage.
17 - CHECK YOUR WEALTH-BUILDING DIRECTION
Look beyond the next six months.
If you’re working towards longer-term financial goals, use your reset as an opportunity to step back and look at the bigger picture.
Consider:
- Net worth
- Savings growth
- Debt reduction
- Superannuation
- Investments
- Long-term goals
The point isn’t to obsess over performance.
It’s to check whether your financial strategy still aligns with your goals, timeframe and circumstances.
For investments, reviewing your overall plan periodically can help you stay aligned with your goals and risk tolerance rather than reacting to every short-term market movement.
Think long term.
Your financial future isn’t built in one month.
18 - ASK THE BIGGER QUESTION
Is your money supporting the life you actually want?
This is where the Mid-Year Money Reset becomes more than a financial exercise.
Because money isn’t just about numbers.
It’s about life.
Maybe you want more travel.
More time.
More security.
A home.
A business.
More experiences with the people you love.
More freedom.
Less stress.
More choice.
Ask yourself:
What do I want my money to make possible during the next six months?
Then ask:
Does my current financial strategy support that?
If it doesn’t, this is your opportunity to realign.
THE 30-MINUTE MID-YEAR MONEY RESET
Don’t have an entire afternoon?
You don’t need one.
Set a timer for 30 minutes and work through this quick reset.
MINUTES 1–5 – KNOW
Write down:
Income: __________
Savings: __________
Debt: __________
Net worth: __________
MINUTES 6–10 – REVIEW
Look at your recent spending.
Ask:
What surprised me?
What worked?
What would I change?
MINUTES 11–15 – REALIGN
Write down your current financial goals.
Circle the three that matter most.
MINUTES 16–20 – LOOK AHEAD
Write down your major upcoming expenses and life events.
MINUTES 21–25 – RESET
Complete:
More of: ______________________
Less of: _______________________
Stop: __________________________
Start: _________________________
MINUTES 26–30 – MOVE FORWARD
Choose one financial action to take this week.
Maybe:
Automate a savings transfer.
Cancel a subscription.
Update your budget.
Create a sinking fund.
Review your debt.
Set a new savings goal.
Organise your financial documents.
Schedule your next money check-in.
One action is enough.
Momentum comes from movement, not perfection.
IF YOU FEEL “BEHIND”
Read this twice.
You are not behind.
You are here.
And here is somewhere you can begin.
Financial progress doesn’t move in a perfectly straight line.
There will be months when you save more.
Months when you save less.
Months when unexpected expenses appear.
Months when everything seems to click.
That’s life.
Your job isn’t to make every month perfect.
Your job is to keep coming back to your strategy.
If January didn’t go to plan, February gave you another opportunity.
If the first quarter was messy, the second quarter gave you another opportunity.
And if the first half of the year didn’t look how you hoped?
The next six months are still yours.
That’s the beauty of a reset.
THE FINANCE STRATEGY METHOD™
KNOW. ORGANISE. PLAN. BUILD. THRIVE.
Your Mid-Year Money Reset is a chance to move through the Finance Strategy Method™ again.
KNOW
Look honestly at your numbers.
ORGANISE
Create order around your accounts, bills, spending and savings.
PLAN
Decide what matters for the next six months.
BUILD
Turn those priorities into consistent actions.
THRIVE
Create a financial life that gives you more confidence, flexibility and choice.
The process doesn’t have to be complicated.
Clarity creates confidence.
And confidence makes it easier to make intentional decisions.
THE QUIET POWER OF A RESET
A reset doesn’t mean you’ve failed.
It means you’re paying attention.
It means you’re willing to pause.
To look honestly at where you are.
To release what no longer works.
To keep what does.
To change direction when necessary.
And to move forward with intention.
There is something incredibly powerful about knowing you can always return to your financial strategy.
You can begin again without starting from scratch.
YOUR MONEY. YOUR NEXT CHAPTER.
The second half of the year doesn’t need to be about doing more.
It can be about doing what matters more.
Save for the goal that matters.
Spend on what brings genuine value.
Prepare for what’s coming.
Build your financial foundation.
Simplify what feels complicated.
Release the financial habits that no longer serve you.
And give your money a clearer direction.
Because your financial life doesn’t need another set of unrealistic rules.
It needs a strategy that fits the life you’re actually living.
So pause.
Review.
Realign.
Reset.
Then keep moving.
Your future doesn’t need you to be perfect.
It needs you to be intentional.
A FINAL MID-YEAR REMINDER
You don’t need to wait until January.
You don’t need to wait until next month.
You don’t need to wait until you earn more.
You don’t need to have everything figured out.
You can make one intentional financial decision today.
One small reset.
One better system.
One clearer goal.
One automatic transfer.
One conversation.
One step.
That’s how financial progress is built.
Not all at once.
But intentionally.
Know your money.
Organise your finances.
Plan your future.
Build your wealth.
Create a life you feel good about.
That is the Finance Strategy Co. way.
Your money. Your strategy. Your future.
Money, but make it intentional.
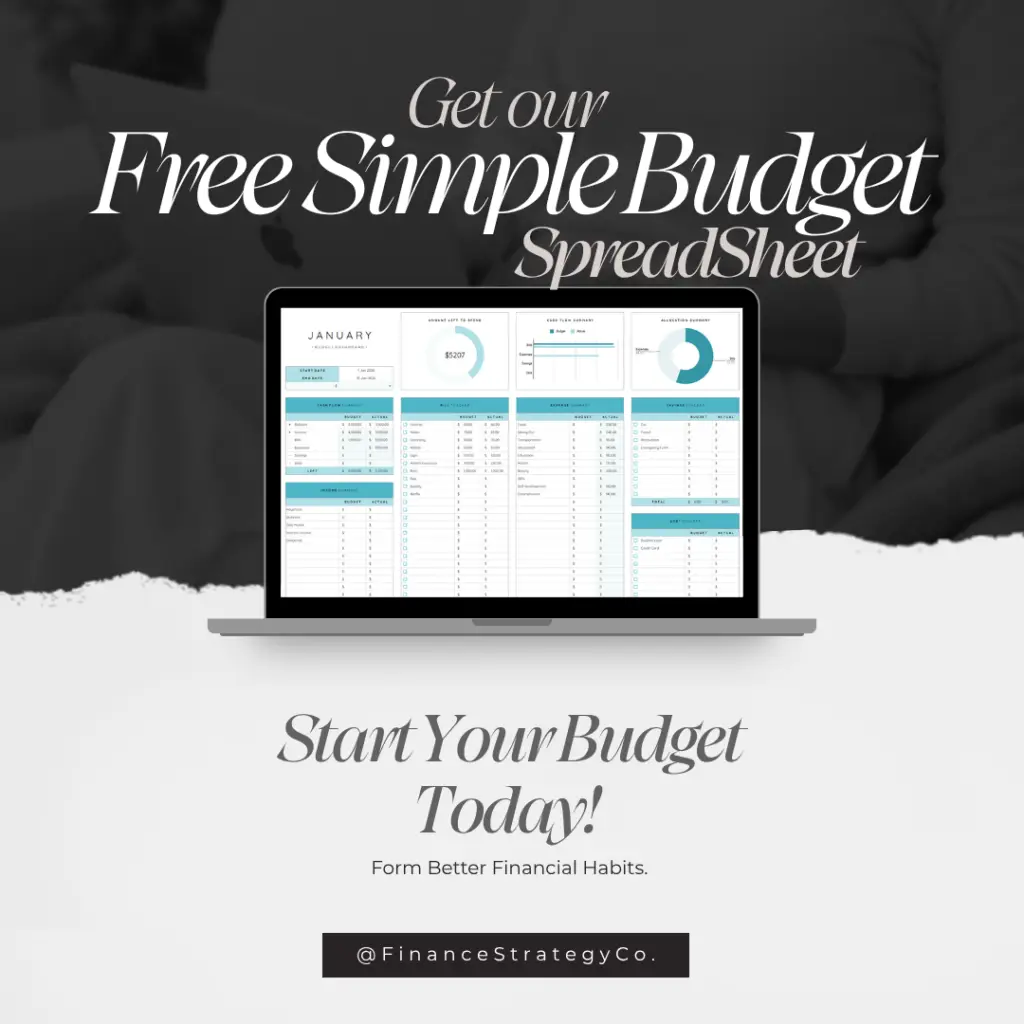
Ready to Elevate Your Money Management?
Finance Strategy Co. creates thoughtfully designed financial tools to help you organise your money, plan ahead, track your progress and build a financial system that fits your life.
Money management, elevated.