
You don't need a huge income. You need a strategy.
There is a version of wealth building that rarely gets talked about.
It doesn’t involve overnight success.
It doesn’t involve a six-figure salary, a perfectly timed investment or becoming obsessed with cutting every little expense.
It’s quieter than that.
It looks like knowing where your money is going.
Spending intentionally.
Creating financial breathing room.
Building savings.
Reducing expensive debt.
Investing consistently when you’re ready.
Using your time wisely.
And making small financial decisions that become increasingly powerful when repeated for years.
Because here’s the truth:
You don’t have to be wealthy to start building wealth.
You can begin with the income you have today.
You can build slowly.
You can make progress without sacrificing every enjoyable part of your life.
And you can create a financial future that looks very different from your financial starting point.
This is wealth building, but without the hype.
What does it actually mean to build wealth?
Wealth isn’t simply about earning a large income.
It’s about gradually building the gap between what you own and what you owe.
That can happen through:
- Growing your savings
- Reducing debt
- Building investments
- Growing superannuation
- Increasing your income
- Owning assets
- Creating financial resilience
- Making your money work towards long-term goals
Your income is important.
But your financial strategy is what determines what happens to the money that comes in.
You could earn more and still feel financially stretched.
Or you can begin building meaningful wealth from an ordinary income by creating a system that consistently directs money towards your future.
Income gives you resources. Strategy gives those resources direction.
First, forget the “average income” comparison
The phrase average income can make wealth building feel like something reserved for someone else.
Someone earning more.
Someone who bought property earlier.
Someone who received an inheritance.
Someone who seems to have their financial life completely figured out.
Comparison isn’t a financial strategy.
Your wealth-building journey needs to be based on:
Your income.
Your expenses.
Your financial responsibilities.
Your goals.
Your timeframe.
Your opportunities.
And your starting point.
You don’t need someone else’s financial life.
You need a strategy for your own.
THE WEALTH-BUILDING FORMULA
Think of wealth building as a series of decisions:
EARN → ORGANISE → PROTECT → INVEST → GROW
EARN
Create income and look for opportunities to increase your earning capacity.
ORGANISE
Know where your money is going and create a system that gives it direction.
PROTECT
Build financial resilience through savings, appropriate protection and sensible debt management.
INVEST
Put long-term money to work in investments that fit your goals, timeframe and comfort with risk.
GROW
Allow time, consistency, increasing contributions and compounding to do more of the heavy lifting.
There is no magic step.
Wealth is built through the combination.
01 - KNOW YOUR STARTING POINT
You can’t build a strategy around numbers you don’t know.
Before thinking about investing, property or becoming financially independent, start with your current financial picture.
Write down:
Income
How much comes into your household?
Expenses
How much does your lifestyle currently cost?
Savings
How much cash have you already accumulated?
Debt
What do you currently owe?
Assets
What do you own that has financial value?
Net worth
What you own minus what you owe.
Cash flow
What’s left after your income covers your expenses?
This is your starting point.
Not your judgement.
Not your worth.
Not your future.
Just your starting point.
And once you know where you are, you can decide where you want to go.
02 - CREATE A GAP BETWEEN INCOME AND SPENDING
This is where wealth building begins.
You don’t need to save every dollar.
You need to create margin.
Margin is the space between what you earn and what you spend.
That space can become:
Savings.
Debt reduction.
Investments.
Financial security.
Future opportunities.
For example, imagine your monthly take-home income is $5,000 and your total spending is $4,700.
That leaves:
$300 of monthly financial margin.
That’s $3,600 over a year before considering any interest, investment returns or changes in your contributions.
Now imagine gradually creating $500 of margin.
Then $700.
Then $1,000.
The objective isn’t to suddenly become incredibly restrictive.
It’s to gradually create more room for your future.
03 - DON'T TRY TO CUT EVERYTHING
Wealth building shouldn’t feel like punishment.
One of the biggest mistakes people make when they decide to build wealth is trying to eliminate every enjoyable expense.
No restaurants.
No holidays.
No coffee.
No entertainment.
No spontaneous purchases.
No fun.
Forever.
That’s not a financial strategy.
That’s financial exhaustion.
And exhaustion rarely creates sustainable habits.
Instead, ask:
What do I want my money to make possible?
Create room for both:
TODAY
and
TOMORROW.
Your budget can include:
- Essentials
- Lifestyle spending
- Fun money
- Savings
- Debt reduction
- Investing
- Future goals
The goal isn’t to create the smallest possible lifestyle.
It’s to create a sustainable one.
04 - BUILD YOUR FINANCIAL FOUNDATION
Before you chase wealth, create stability.
Wealth building becomes much easier when your financial foundation is strong.
Start by focusing on the basics:
01 – Know your cash flow
Understand what’s coming in and going out.
02 – Build emergency savings
Create a financial buffer for unexpected expenses.
03 – Manage high-cost debt
Understand the interest you’re paying and create a realistic strategy for reducing expensive debt.
04 – Get organised
Know your bills, accounts, subscriptions and financial commitments.
05 – Create a system
Automate what you can and establish regular money check-ins.
This foundation may not feel glamorous.
But it’s incredibly valuable.
Financial security is part of wealth.
05 - MAKE SAVING AUTOMATIC
Don’t rely on motivation.
One of the simplest ways to build wealth is to make saving consistent.
Instead of saving whatever happens to be left at the end of the month, consider setting up an automatic transfer after you receive your income.
You decide the amount.
You choose the frequency.
Then your system does the work.
For example:
$50 per week = $2,600 per year
$100 per week = $5,200 per year
$200 per week = $10,400 per year
That’s before considering interest or investment returns.
And if your income increases later?
You can increase the contribution.
Small numbers become more interesting when you give them time.
06 - USE TIME TO YOUR ADVANTAGE
Your greatest wealth-building asset may not be your income.
It may be time.
Compounding allows returns to generate further returns over time, meaning money can potentially grow on both your original contributions and previous growth. The longer your money remains invested, the more opportunity there is for this effect to work.
This is why starting with a smaller amount today can be more meaningful than waiting until you feel “rich enough” to begin.
Consider two people.
PERSON A
Waits ten years until they feel financially ready.
PERSON B
Starts with a manageable amount today and gradually increases contributions as their circumstances improve.
Person B has given their money something Person A can’t buy later:
More time.
This doesn’t mean investing is guaranteed to make money.
Markets rise and fall, and investments carry risk.
It simply means that time and consistency matter.
07 - INCREASE YOUR SAVINGS RATE AS YOUR INCOME GROWS
Let your lifestyle grow slower than your income.
Imagine you receive a pay rise.
You could allow the entire increase to disappear into lifestyle upgrades.
Or you could decide:
“Part of this belongs to my future.”
Maybe you increase your savings.
Maybe you increase debt repayments.
Maybe you increase long-term investments.
Maybe you divide the increase between enjoying today and building tomorrow.
This is where lifestyle inflation becomes important.
You don’t have to refuse every upgrade.
Just don’t let every increase in income become an increase in lifestyle.
A simple principle:
Earn more → enjoy some → direct some towards your future.
08 - INVEST FOR THE LONG TERM
Saving and investing have different jobs.
Savings can provide liquidity and financial security.
Investing can help you pursue longer-term growth.
The right approach depends on what the money is for.
For shorter-term goals, lower-risk options may be more appropriate.
For longer-term goals, investments such as shares or property can offer greater growth potential but also come with greater risk and volatility.
This is why the question shouldn’t simply be:
“What should I invest in?”
Start with:
“What am I investing for?”
Then consider:
How long do I have?
How much risk can I tolerate?
How much volatility can I realistically handle?
What investment strategy fits those circumstances?
Your investment choices should support your financial strategy, not replace it.
09 - THINK ABOUT DIVERSIFICATION
Don’t build your entire financial future around one thing.
Diversification means spreading investments across different assets, investments, sectors or geographic markets rather than relying heavily on one.
The reason is simple:
One investment can struggle without taking your entire portfolio down with it.
Different assets can perform differently in different conditions.
Diversification doesn’t eliminate investment risk.
But it can help reduce the impact of poor performance from one investment or area of the market.
For someone building wealth over decades, understanding diversification is far more valuable than chasing the investment everyone happens to be talking about this month.
Build a strategy, not a trend.
10 - DON'T FORGET YOUR SUPERANNUATION
Your future wealth isn’t only outside your super.
For Australians, superannuation is an important part of long-term wealth building.
Employer super contributions are currently 12% of ordinary time earnings, and from 1 July 2026 employers are required to pay super at the same time as wages under Payday Super.
Your super fund invests your money over the long term, and you can generally choose from different investment options depending on the fund.
So don’t let your super become “set and forget.”
Consider reviewing:
- Your super balance
- Your fees
- Your investment option
- Your insurance
- Whether you have multiple accounts
- Whether your super strategy still fits your circumstances
Super is designed for retirement and generally isn’t money you can access whenever you want, so it needs to be considered separately from money you’re saving for shorter-term goals.
Your wealth strategy should include the money you can’t see in your everyday bank account.
11 - Build Assets, Not Just A Bigger Paycheck
Income is important. Ownership is powerful.
A higher income can absolutely improve your financial position.
But long-term wealth is also about what you accumulate and own.
That might include:
- Cash savings
- Superannuation
- Shares
- ETFs
- Property
- Business interests
- Other investments
The goal isn’t to own everything.
It’s to gradually build assets that can contribute to your long-term financial position.
This is one of the biggest mindset shifts in wealth building:
Don’t only ask, “How much do I earn?”
Ask:
“What am I building?”
12 - INVEST IN YOUR ABILITY TO EARN MORE
Your income is an asset too.
Sometimes the most powerful wealth-building move isn’t reducing another $20 from your grocery bill.
It’s increasing your earning capacity.
Consider:
- Developing new skills
- Negotiating your salary
- Changing roles
- Professional qualifications
- Starting a side business
- Freelancing
- Creating additional income streams
- Building a business
- Developing expertise
You don’t have to turn your entire life into a side hustle.
But it’s worth asking:
What could increase my earning potential over the next three to five years?
An additional $5,000 or $10,000 of annual income can create meaningful financial opportunities if you intentionally direct part of it towards your goals.
Sometimes the biggest money-saving strategy is earning more.
13 - BE CAREFUL WITH LIFESTYLE INFLATION
More income doesn’t automatically mean more wealth.
Imagine your income increases by $10,000.
Your lifestyle increases by $9,500.
You earned more.
But your financial margin barely changed.
Now imagine your lifestyle increases by $4,000 and you direct the remaining $6,000 towards your financial priorities.
Your income increased.
And your wealth-building capacity increased with it.
You don’t have to live like you earn half your salary.
Just allow your wealth-building rate to grow alongside your lifestyle.
14 - CREATE A “WEALTH GAP”
Give future-you a percentage of every increase.
You don’t need a complicated formula.
Create a personal rule.
For example:
Every time my income increases, part of the increase goes towards my future.
That could mean:
- 25% towards investing
- 25% towards savings
- 25% towards debt
- 25% towards lifestyle
Or a completely different split.
The point isn’t the percentage.
The point is having a rule before the money arrives.
That makes wealth building a system rather than a decision you have to make every payday.
15 - GIVE EVERY FINANCIAL GOAL ITS OWN JOB
Don’t mix everything together.
One reason money can feel chaotic is because every financial goal competes for the same dollars.
Instead, give your money different jobs.
PROTECT
Emergency savings.
PLAN
Upcoming expenses and sinking funds.
REDUCE
Debt repayment.
BUILD
Long-term investments and wealth.
ENJOY
Lifestyle spending.
Now your money has direction.
This doesn’t necessarily mean you need five separate bank accounts.
It’s a way of thinking.
Money becomes easier to manage when you know what it’s there to do.
16 - LET YOUR INVESTMENTS WORK QUIETLY
Wealth doesn’t need to be exciting.
There is a temptation to constantly check investments.
Buy something.
Sell something.
Follow the market.
Change strategies.
Chase the next opportunity.
But wealth building isn’t supposed to be entertaining.
It is supposed to support your long-term goals.
A well-designed investment strategy considers your goals, timeframe and tolerance for risk, with diversification helping manage portfolio risk.
You don’t need to make money exciting.
You need to make your financial system sustainable.
17 - STOP CHASING QUICK WEALTH
If it sounds too good to be true, pause.
Building wealth slowly can feel frustrating when social media is filled with stories of people supposedly becoming rich overnight.
But sustainable wealth rarely looks dramatic.
It looks like:
Regular contributions.
Long-term thinking.
Avoiding unnecessary financial mistakes.
Building skills.
Increasing income.
Owning productive assets.
Protecting your downside.
Staying invested according to your strategy.
Repeating the process.
There will always be another trend.
Another investment.
Another “secret.”
Another person promising extraordinary returns.
You don’t need it.
You need a strategy you can actually stick to.
18 - TRACK YOUR NET WORTH
Watch the bigger picture.
Your bank balance only tells you part of the story.
Net worth gives you another perspective.
Remember:
Assets − Liabilities = Net Worth
Track it periodically.
Not obsessively.
Perhaps quarterly or annually.
Look for the direction.
Is your net worth growing?
Are your debts decreasing?
Are your savings increasing?
Are your investments growing over time?
Are you building more financial resilience?
Your net worth isn’t your identity.
It’s simply another number that can help you understand your financial progress.
19 - DON'T WAIT UNTIL YOU “HAVE MORE MONEY”
Start with the money you have.
One of the biggest myths about wealth building is:
“I’ll start when I earn more.”
Then you earn more.
And your lifestyle grows.
Then you think:
“I’ll start when I earn even more.”
And the cycle continues.
You don’t need to wait for the perfect income.
Start by learning how to manage the income you have.
Then when your income grows, you’ll already have the habits and systems to direct it.
Build the system before you build the fortune.
WHAT IF YOU CAN ONLY INVEST A SMALL AMOUNT?
That’s okay.
Maybe your starting point is:
$10 a week.
Maybe it’s:
$25 a week.
Maybe it’s:
$50 a fortnight.
The number matters less than whether the amount is realistic and sustainable for your circumstances.
Don’t underestimate small beginnings.
A small contribution can teach you something incredibly valuable:
How to become someone who consistently builds wealth.
And as your circumstances change, your contribution can change too.
A SIMPLE WEALTH-BUILDING ROADMAP
You don’t need to do everything at once.
Think about your journey in stages.
STAGE ONE – GET CLEAR
Know your income.
Know your expenses.
Know your debt.
Know your savings.
Know your net worth.
STAGE TWO – CREATE STABILITY
Build financial breathing room.
Create emergency savings.
Organise your bills.
Create a realistic budget.
Manage expensive debt.
STAGE THREE – CREATE MOMENTUM
Automate savings.
Increase your savings rate.
Set financial goals.
Increase your income where possible.
Start investing when appropriate.
STAGE FOUR – BUILD
Grow your assets.
Reduce debt.
Build superannuation.
Invest consistently.
Track your net worth.
STAGE FIVE – THRIVE
Create financial flexibility.
Increase your choices.
Plan for your long-term goals.
Build a lifestyle supported by your financial strategy.
There is no race.
Your timeline is yours.
THE FINANCE STRATEGY METHOD™
KNOW. ORGANISE. PLAN. BUILD. THRIVE.
Building wealth on an average income is exactly what the Finance Strategy Method™ is designed to support.
KNOW
Understand your financial starting point.
ORGANISE
Create a system for your income, expenses, savings and financial commitments.
PLAN
Choose the goals that matter and create a strategy for reaching them.
BUILD
Save, reduce debt, invest and grow your assets.
THRIVE
Use your money to create greater freedom, flexibility and choice.
Notice what isn’t on the list:
Get rich overnight.
Never spend money on fun.
Follow every investment trend.
Become obsessed with your finances.
Because that’s not the goal.
The goal is to create a financial life that works.
THE 30-MINUTE WEALTH RESET
Start here.
You don’t need an elaborate five-year wealth plan today.
Give yourself 30 minutes.
MINUTES 1–5 – KNOW
Write down:
Monthly income: __________
Monthly expenses: __________
Savings: __________
Debt: __________
Net worth: __________
MINUTES 6–10 – FIND YOUR GAP
Calculate:
Income − spending = financial margin
Then ask:
How much could I realistically direct towards my future?
MINUTES 11–15 – PROTECT
Ask:
☐ Do I have emergency savings?
☐ Do I have a plan for expensive debt?
☐ Are my finances organised?
MINUTES 16–20 – BUILD
Choose one:
☐ Increase savings
☐ Increase debt repayments
☐ Start or review an appropriate investment strategy
☐ Review super
☐ Increase income
☐ Build a new financial skill
MINUTES 21–25 – GROW
Ask:
How could I increase my financial margin over the next 12 months?
Write down three ideas.
01. __________________
02. __________________
03. __________________
MINUTES 26–30 – CHOOSE ONE MOVE
What is the one thing you will do this week?
________________________________
Don’t create a 25-step plan.
Choose one move. Then repeat.
WHAT DOES WEALTH ACTUALLY MEAN TO YOU?
This is the question most wealth-building articles forget to ask.
What are you actually trying to build?
Maybe it’s:
A home.
More travel.
Financial independence.
A business.
The ability to work less.
More time with your family.
A comfortable retirement.
The freedom to say no.
The ability to handle an unexpected expense without panic.
A life with more choices.
Or simply the feeling of knowing you’re okay.
Your definition of wealth matters.
Because if you don’t define what you’re building, it’s very easy to spend your entire life chasing a number.
And there will always be another number.
THE QUIET SIDE OF WEALTH
Real wealth can look surprisingly ordinary.
It can look like:
A savings account that keeps growing.
A manageable mortgage.
A disappearing debt balance.
A healthy super balance.
Regular investment contributions.
A budget that doesn’t make you miserable.
A financial system that runs quietly in the background.
Knowing you can handle an unexpected expense.
Having choices.
Having time.
Having less financial stress.
That’s wealth too.
Not flashy.
Not performative.
Just quietly powerful.
YOU DON'T NEED TO LOOK WEALTHY
You need to become financially stronger.
There is a difference.
Looking wealthy can involve spending money.
Building wealth often involves doing something much less visible:
Keeping some of it.
Saving some of it.
Investing some of it.
Using some of it to reduce financial obligations.
Allowing some of it to compound.
The car may be visible.
The investment account isn’t.
The designer purchase may be visible.
The growing net worth isn’t.
The expensive holiday may be visible.
The financial flexibility it took to afford it responsibly isn’t.
Wealth doesn’t always look impressive from the outside.
Sometimes it simply feels like freedom on the inside.
THE LONG GAME
You may not become wealthy this year.
That’s okay.
You don’t need to.
You are building something that may take decades to fully unfold.
And that’s precisely why you don’t need to rush.
You need consistency.
You need patience.
You need a strategy that fits your actual life.
You need the ability to adjust when life changes.
And you need to keep moving.
Small decisions become powerful when they are repeated for long enough.
YOUR MONEY. YOUR STRATEGY. YOUR FUTURE.
Building wealth on an average income isn’t about discovering a secret.
It’s about making your ordinary money work harder over time.
Know your numbers.
Create financial margin.
Build your foundation.
Protect what you’ve built.
Save consistently.
Invest thoughtfully when appropriate.
Grow your earning potential.
Avoid unnecessary lifestyle inflation.
Give your money direction.
And let time do some of the heavy lifting.
You don’t need to become a different person.
You don’t need to live a joyless life.
You don’t need to chase every opportunity.
You need a strategy you can live with.
Because wealth isn’t simply about having more.
It’s about having more choices.
More flexibility.
More security.
More freedom.
More time.
And ultimately, more ability to create a life that feels like yours.
Start with what you have.
Build with what you have.
Then let your strategy evolve as you grow.
That’s wealth building, the Finance Strategy Co. way.
Your money. Your strategy. Your future.
Money, but make it intentional.
Ready to Take Control of Your Money?
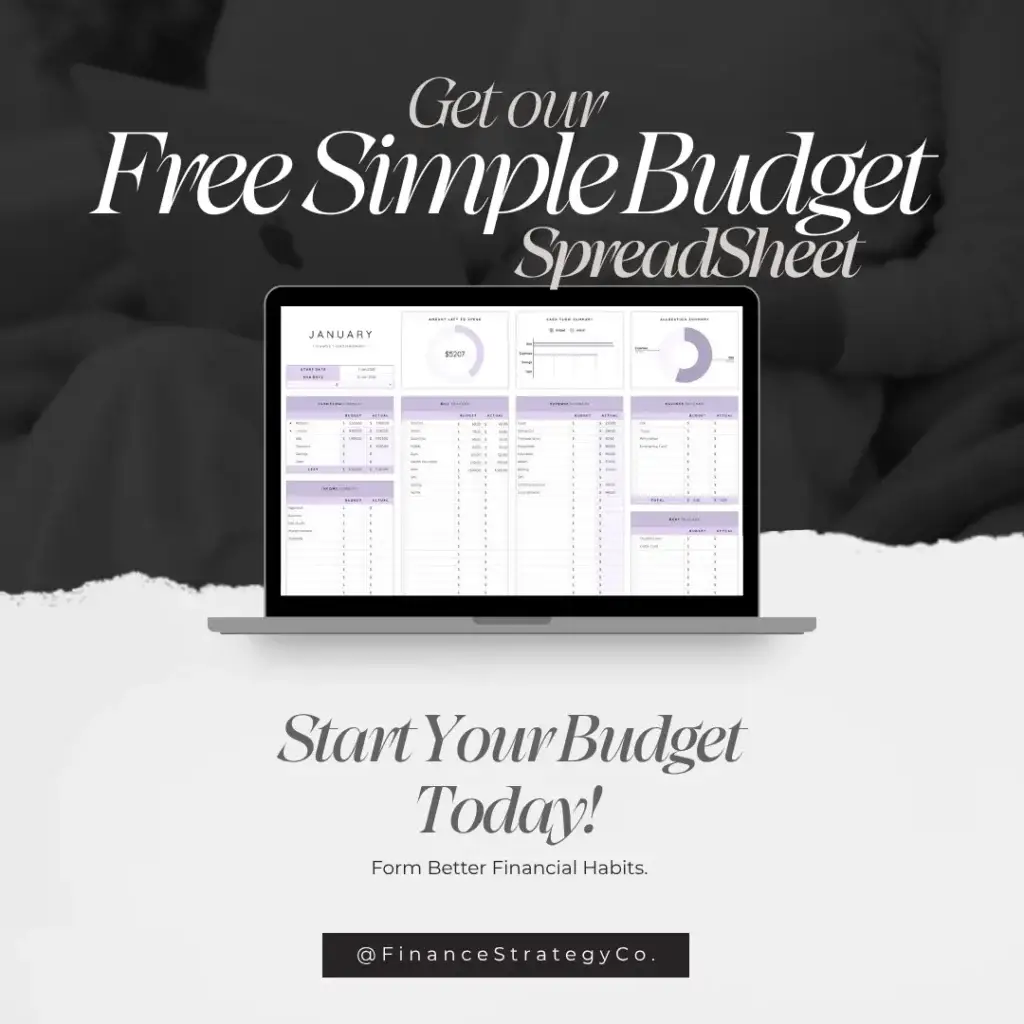
Finance Strategy Co. creates thoughtfully designed financial tools to help you organise your money, track your debt, plan your goals and build a financial strategy around the life you actually want.
Money management, elevated.