
You don't need to control every dollar. You need to understand your money.
There is a particular kind of stress that comes from not quite knowing where you stand financially.
You might earn a decent income, but still feel like your money disappears.
You might have a budget, but rarely look at it.
You might be saving, but wonder whether you’re saving enough.
You might have goals for the future, but feel like everyday expenses keep getting in the way.
Or perhaps nothing is particularly wrong with your finances, you simply don’t feel in control of them.
And that feeling matters.
Because financial confidence isn’t only about how much money you have.
It’s also about knowing what is happening with the money you have.
Knowing what is coming in.
Knowing what is going out.
Knowing what needs to be paid.
Knowing what you’re saving for.
Knowing what you’re building.
And, perhaps most importantly, knowing that your money decisions are intentional rather than reactive.
You don’t need a perfect financial life.
You need a clearer one.
Welcome to a better relationship with your money.
What does it actually mean to feel in control of your money?
Being in control of your money doesn’t mean tracking every coffee, never making an unnecessary purchase or saying no to everything you enjoy.
It doesn’t mean having a six-figure salary.
And it certainly doesn’t mean being perfect.
Financial control is much simpler than that.
It means you have enough awareness of your finances to make decisions with intention.
You know your financial commitments.
You understand your spending.
You have a plan for your savings.
You know what you’re working towards.
You have systems in place for the things that need to happen regularly.
And when something changes, you know how to adjust.
Control comes from clarity.
And clarity comes from knowing your money.
Start with curiosity, not criticism.
If you currently feel disconnected from your finances, the first step isn’t to cut your spending.
It’s to look.
Open your banking app.
Look at your accounts.
Review your recent transactions.
Check your bills.
Look at your subscriptions.
Review your savings.
Check your debt.
And take a moment to understand what your money has actually been doing.
This isn’t an opportunity to judge yourself.
It’s an opportunity to gather information.
There may be purchases you wouldn’t make again.
There may be subscriptions you’ve forgotten about.
There may be expenses that have increased.
There may also be things you’re doing incredibly well.
Maybe you’ve been consistently saving.
Maybe you’ve reduced your debt.
Maybe you’ve created better spending habits.
Maybe you’re simply more aware than you were six months ago.
You can’t create a strategy for money you refuse to look at.
So start there.
Look.
Learn.
Then decide.
01 - Know your numbers
You don’t need to know every financial number imaginable.
But you should know the numbers that shape your everyday financial life.
Start with:
Your income
How much money actually comes into your household?
Consider your regular take-home income and any income that varies.
If your income isn’t consistent, use a realistic average or create a plan based on your more conservative income level.
Your essential expenses
What does it cost to run your life?
Think about:
- Housing
- Groceries
- Utilities
- Transport
- Insurance
- Healthcare
- Debt repayments
- Childcare or education
- Other essential commitments
Your flexible spending
What do you choose to spend money on?
This could include:
- Dining out
- Shopping
- Entertainment
- Beauty
- Hobbies
- Travel
- Takeaway
- Experiences
Your savings
What are you currently saving?
And more importantly, what are you saving for?
Your debt
What do you owe?
Know your balances, repayments and interest rates so you can understand the bigger picture.
Your net worth
Your net worth gives you another perspective on your financial position by looking at what you own compared with what you owe.
You don’t need to obsess over the number.
Simply knowing where you stand can help you understand the bigger financial picture.
02 - Create a budget that reflects your actual life
A budget shouldn’t feel like a punishment.
It should feel like a plan.
A good budget answers a simple question:
Where do I want my money to go?
Instead of creating an unrealistic budget based on the person you think you should be, create one based on the life you actually live.
If you spend money on coffee every morning, include it.
If you love going out for dinner, make room for it.
If you travel regularly, create a travel fund.
If you have annual expenses, plan for them.
If you want to save more, give saving a place in your budget.
The goal isn’t to eliminate everything enjoyable.
The goal is to make your spending intentional.
Your budget should create boundaries without making your life feel smaller.
03 - Give your money a job
One of the easiest ways to feel more financially organised is to stop thinking about your money as one big pool.
Instead, give different amounts different purposes.
At Finance Strategy Co., we like to think about money through five simple jobs:
LIVE
The money that supports your everyday life.
Housing. Food. Transport. Bills. Essentials.
ENJOY
The money that allows you to actually enjoy your life.
Restaurants. Shopping. Experiences. Hobbies. Holidays.
PROTECT
The money that creates financial breathing room.
Emergency savings. Insurance. Financial buffers.
PLAN
The money connected to future goals.
Upcoming purchases. Annual expenses. Sinking funds. Financial milestones.
BUILD
The money helping you create your longer-term financial future.
Debt reduction, investing, superannuation and other wealth-building goals appropriate to your circumstances.
When your money has a purpose, it becomes easier to understand what you can spend, and what you shouldn’t.
Your money isn’t just money.
It’s a collection of decisions about the life you’re creating.
04 - Know where your money is going
You don’t need to track every transaction forever.
But spending awareness can completely change the way you experience your finances.
Spend some time reviewing your recent transactions.
Look for:
Patterns.
Subscriptions.
Convenience spending.
Impulse purchases.
Recurring expenses.
Forgotten expenses.
Spending that genuinely brings value.
And spending that doesn’t.
The goal isn’t to find everything you can cut.
It’s to understand your behaviour.
Because sometimes the problem isn’t that you’re spending too much.
It’s that you’re spending without a plan.
Once you know where your money is going, you can make better decisions about where you want it to go next.
05 - Create a simple bill system
Few things make you feel less in control than constantly wondering:
“Did I pay that bill?”
Create one simple system for your recurring expenses.
You might keep a list of:
- Bill
- Amount
- Due date
- Payment method
- Frequency
Include monthly, quarterly and annual expenses.
Then consider whether certain bills can be automated or whether you can set aside money regularly for larger, less frequent expenses.
The goal is simple:
Stop relying on memory.
Your financial system should remember the boring stuff for you.
06 - Separate spending from saving
One account doesn’t necessarily have to do everything.
Creating some separation between your everyday spending and your savings can make your financial system easier to understand.
For example:
Everyday → regular spending
Bills → recurring commitments
Savings → future goals
You could also create separate savings buckets for specific goals such as:
- Emergency fund
- Holiday
- Car
- Home
- Annual expenses
- Personal goals
The exact structure doesn’t matter as much as having a system that makes sense to you.
And when possible, automate your savings so your financial progress isn’t dependent on remembering to transfer money every payday. Automated transfers can make saving more consistent and reduce the number of decisions you need to make.
07 - Create a financial buffer
One of the biggest differences between feeling financially fragile and feeling financially secure can be having money set aside for the unexpected.
Your emergency fund doesn’t need to appear overnight.
Start where you are.
Maybe your first milestone is:
$100
Then:
$250
Then:
$500
Then:
$1,000
From there, you can continue building according to your circumstances and financial priorities.
The purpose isn’t simply to reach an impressive number.
It’s to create breathing room.
Because when something unexpected happens, you want your first thought to be:
“Okay. I have a plan for this.”
Not:
“How am I going to pay for this?”
08 - Stop trying to remember everything
Financial organisation isn’t about having an incredible memory.
It’s about creating systems.
Put your important financial information somewhere you can easily access it.
Create a simple financial dashboard.
Keep track of:
- Account balances
- Bills
- Subscriptions
- Savings goals
- Debt
- Net worth
- Upcoming expenses
- Financial goals
You don’t need seventeen spreadsheets.
You need one clear place to see your financial life.
This is one of the quiet luxuries of financial organisation.
You don’t have to wonder.
You can simply look.
09 - Create a weekly money check-in
You don’t need to spend hours managing your money.
Try creating a simple weekly money ritual instead.
This is the idea behind The Sunday Money Reset™.
Set aside 15–30 minutes once a week.
Make yourself a coffee.
Open your budget.
Take a breath.
Then check:
MONEY
What came in this week?
SPENDING
Where did my money go?
BILLS
What’s coming up?
SAVINGS
Did I move money towards my goals?
GOALS
Am I still moving in the right direction?
LIFE
Is there anything coming up that I need to prepare for?
That’s it.
No shame.
No complicated calculations.
No starting your entire financial life from scratch.
Just a small check-in.
Because small, consistent awareness is often more powerful than occasional financial panic.
10 - Create a monthly money date
Your weekly check-in keeps you connected.
Your monthly money date lets you zoom out.
Once a month, look at your bigger picture.
Ask:
What did I spend?
What did I save?
Did I stay within my plan?
What surprised me?
What changed?
What needs adjusting?
What financial goal am I working towards?
What do I want next month to look like?
Your financial system should evolve with your life.
Your income changes.
Your expenses change.
Your priorities change.
Your goals change.
Your budget should be allowed to change too.
Adjusting your plan isn’t failing.
It’s strategy.
11 - Choose your financial priorities
Trying to work on everything at once can leave you feeling like you’re making progress on nothing.
Instead, choose a few priorities.
For example:
Priority One
Build a $1,000 financial buffer.
Priority Two
Pay down a particular debt.
Priority Three
Save for a holiday.
Or perhaps your priorities are:
Save more.
Spend more intentionally.
Organise my finances.
Build my net worth.
Prepare for a major life goal.
The right priorities are personal.
You don’t need to copy someone else’s financial goals.
Your money strategy should reflect your life.
12 - Create more financial margin
Financial margin is the space between what comes in and what needs to go out.
And that space matters.
It gives you options.
It can allow you to save.
It can help you handle unexpected expenses.
It can give you room to work towards goals.
It can create breathing space when life changes.
Creating margin doesn’t necessarily mean cutting everything you love.
It could mean:
- Reviewing recurring expenses
- Reducing spending that doesn’t add value
- Increasing income
- Automating savings
- Planning for irregular expenses
- Avoiding unnecessary debt
- Being more intentional with lifestyle upgrades
Think of margin as financial breathing room.
You don’t need every dollar assigned to something immediately.
Sometimes the most valuable job for your money is simply giving your future self more options.
13 - Give yourself permission to enjoy your money
This one matters.
Because financial control should never mean financial deprivation.
You are allowed to enjoy your money.
You are allowed to buy things you love.
You are allowed to travel.
You are allowed to order the nice dinner.
You are allowed to spend money on experiences.
The difference is intention.
Instead of asking:
“Am I allowed to spend this?”
Try asking:
“Is this something I genuinely value?”
“Does it fit within my plan?”
“Will I be happy I spent this money?”
If the answer is yes, enjoy it.
A healthy financial strategy makes room for both today and tomorrow.
14 - Create a "More of This / Less of That" list
This is one of the simplest ways to make your finances feel more personal.
Write two lists.
MORE OF THIS
Maybe:
- Saving
- Travel
- Experiences
- Financial security
- Investing
- Quality
- Time
- Health
- Family
- Freedom
- Experiences that matter
LESS OF THAT
Maybe:
- Impulse shopping
- Forgotten subscriptions
- Convenience spending
- Comparison spending
- Buying things because they’re on sale
- Spending to keep up
- Financial clutter
- Purchases you regret
This isn’t about creating strict rules.
It’s about creating direction.
Your spending becomes much easier to understand when you know what you actually want more of.
15 - Know your financial "why"
Numbers are useful.
But they aren’t enough.
You need a reason.
Why do you want to feel more in control of your money?
Maybe you want:
Freedom.
Security.
A home.
Travel.
More choices.
Less stress.
The ability to change careers.
To build a business.
To support your family.
To retire comfortably.
To create a life that feels like yours.
Your financial goals become much more meaningful when they’re connected to something bigger than a number.
You’re not just saving $10,000.
You’re creating a future where something becomes possible.
You’re not just paying down debt.
You’re creating more financial freedom.
You’re not just tracking your spending.
You’re learning how to direct your money towards the life you actually want.
The Finance Strategy Co. approach to feeling more in control
At Finance Strategy Co., we believe financial confidence starts with a simple framework:
KNOW → ORGANISE → PLAN → BUILD → THRIVE
KNOW
Understand your income, expenses, spending, savings, debt and financial position.
ORGANISE
Create simple systems for your accounts, bills, subscriptions, savings and financial information.
PLAN
Give your money direction through budgets, goals, priorities and intentional spending.
BUILD
Build savings, reduce debt, strengthen your financial habits and work towards your bigger financial goals.
THRIVE
Create a financial life that gives you greater confidence, flexibility, choice and freedom.
You don’t have to master all five stages today.
You simply need to know which stage you’re ready to work on next.
Your 30-Minute Money Control Reset
If your finances currently feel a little chaotic, don’t try to fix everything today.
Set a timer for 30 minutes.
Put your phone away.
Make a coffee.
Open your banking app and your budget.
Then:
01 – CHECK YOUR BALANCES
Know what you currently have.
02 – REVIEW YOUR RECENT SPENDING
Look for patterns rather than judging purchases.
03 – CHECK UPCOMING BILLS
Know what’s coming before it arrives.
04 – CHECK YOUR SAVINGS
Are you moving towards your current savings goals?
05 – CHECK YOUR DEBT
Know what you owe and what repayments are coming up.
06 – CHOOSE ONE PRIORITY
What is the most important financial thing to focus on next?
07 – MAKE ONE MONEY MOVE
Transfer money to savings.
Cancel an unused subscription.
Update your budget.
Schedule a payment.
Set a financial goal.
Whatever makes sense for you.
Then stop.
You don’t need to rebuild your entire financial life in one afternoon.
One intentional action is still progress.
The signs you're becoming more in control of your money
Financial control doesn’t always look like a bigger bank balance.
Sometimes it looks like:
You know when your bills are due.
You know what you’re spending.
You have savings with a purpose.
You aren’t constantly surprised by your account balance.
You have fewer financial decisions to make.
You have a system for recurring expenses.
You check your finances regularly.
You know your priorities.
You can enjoy spending without unnecessary guilt.
You can say no to purchases that don’t matter to you.
You can say yes to the ones that do.
You have a plan for the future.
And when something changes, you know how to adjust.
That’s financial confidence.
What if your finances are currently a mess?
Start anyway.
There is no perfect starting point.
Maybe you have debt.
Maybe you’ve overspent.
Maybe you haven’t saved anything.
Maybe you have no idea what your subscriptions cost.
Maybe your budget hasn’t been opened in six months.
Maybe you’re living from payday to payday.
None of that means you’re bad with money.
It simply means you have information to work with.
And information is powerful.
Don’t make your first financial goal:
“Fix everything.”
Make it:
“Understand what’s happening.”
Then:
Organise it.
Then:
Create a plan.
Then:
Take the next step.
You don’t need shame to create change.
You need clarity.
The quiet luxury of feeling financially organised
There is something deeply comforting about knowing where you stand.
Knowing your bills are covered.
Knowing what you’re saving for.
Knowing what you can spend.
Knowing what you’re building.
Knowing that an unexpected expense won’t necessarily derail everything.
Knowing that your money has somewhere to go.
That is a kind of financial luxury that has nothing to do with designer labels, expensive cars or impressive bank balances.
It’s the quiet luxury of being prepared.
Of having options.
Of understanding your money.
Of being able to make decisions without constantly wondering whether you can afford them.
Financial confidence is quiet.
You don’t have to prove it to anyone.
Your money doesn't need more rules. It needs a strategy.
Feeling more in control of your money isn’t about becoming stricter.
It’s about becoming more intentional.
Know your numbers.
Organise your financial life.
Create a budget that reflects your reality.
Give your money a purpose.
Build systems that make the boring things easier.
Create financial breathing room.
Save for what matters.
Spend on what you value.
And give yourself permission to enjoy the life you’re building along the way.
You don’t need to become a completely different person to become better with money.
You simply need a system that helps you make better decisions consistently.
Because the goal isn’t to spend your life thinking about money.
The goal is to create a financial system that gives you more space to live your life.
And that is what feeling in control really means.
Your Money. Your Strategy. Your Future.
You don’t need to have everything figured out.
You don’t need the perfect budget.
You don’t need to know exactly what your financial future will look like.
You simply need to know where you are, decide where you want to go and create a strategy that helps you move in that direction.
Start small.
Stay curious.
Keep checking in.
Adjust when life changes.
Celebrate the progress that nobody else can see.
Because financial progress isn’t always dramatic.
Sometimes it’s simply opening your banking app without feeling anxious.
Sometimes it’s seeing money in your savings account.
Sometimes it’s saying no to something that doesn’t matter so you can say yes to something that does.
Sometimes it’s knowing that you’re finally building a financial life that feels like yours.
Your money deserves a strategy.
Finance Strategy Co.
Money, but make it intentional.
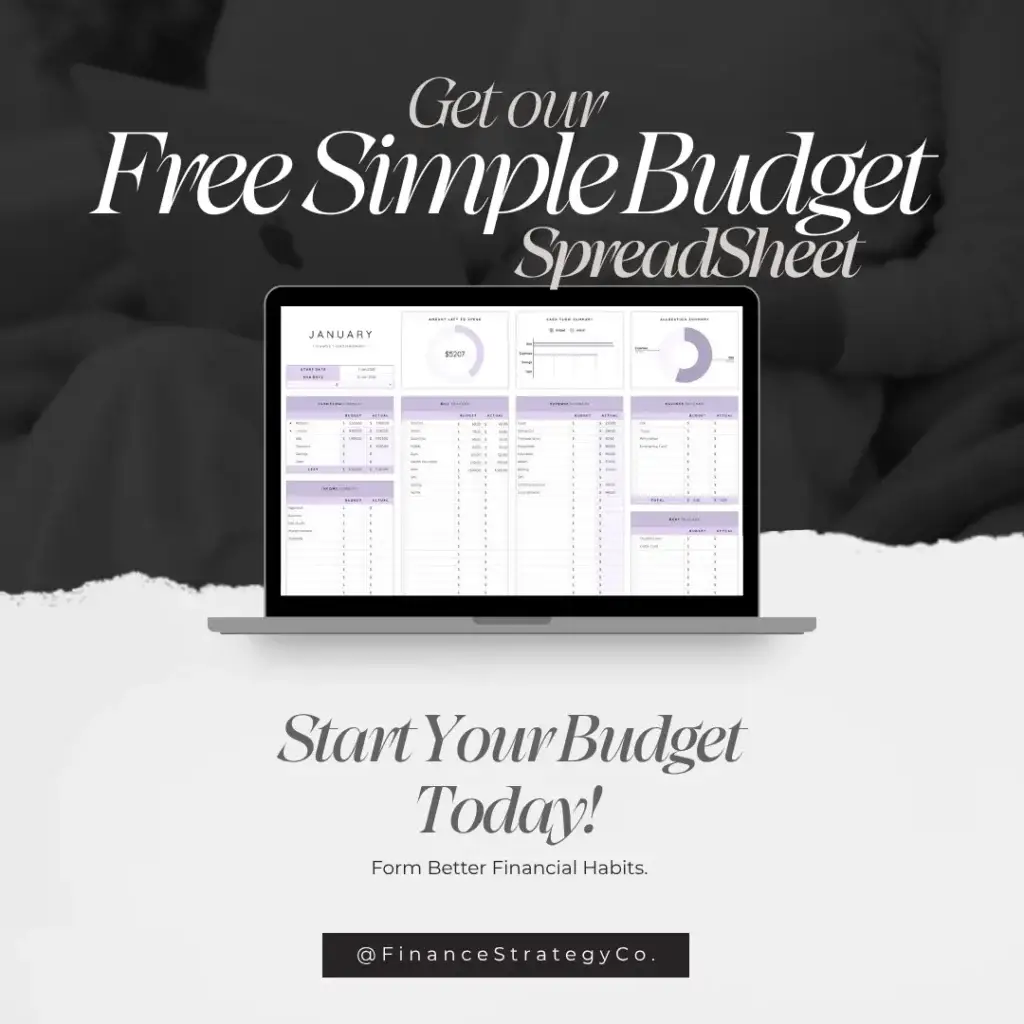
Ready to Make Your Money Feel More Organised?
Your budget is easier to maintain when your financial system is simple.
Explore Finance Strategy Co.'s thoughtfully designed budgeting and financial organisation tools to help you plan your spending, track your expenses, manage your goals and create a financial system that fits your life.
Your money deserves a strategy.