
Sometimes the number that changes your money mindset isn't your income.
It's your net worth.
We spend so much time talking about income.
How much we earn.
How much we should be earning.
Whether our salary is “enough.”
Whether we can afford the lifestyle we want.
But income only tells you what is coming in.
It doesn’t necessarily tell you how strong your overall financial position is.
That’s where net worth becomes interesting.
Your net worth gives you a broader view of your financial life by looking at what you own compared with what you owe. In simple terms, it is your total assets minus your total liabilities.
And once you start paying attention to that number, something interesting can happen.
Your perspective begins to change.
You stop looking at money purely through the lens of income and spending.
You start thinking about ownership, progress, financial strength, future options and the life you’re building.
That shift can be incredibly powerful.
What exactly is net worth?
Let’s start with the basics.
Your net worth is a snapshot of your overall financial position.
Your assets
These are things you own that have financial value.
Depending on your circumstances, they could include:
- Savings
- Investments
- Property
- Superannuation
- Other valuable assets
Your liabilities
These are debts or financial obligations you owe.
They might include:
- Mortgage
- Personal loans
- Car loans
- Credit card balances
- Other debts
The basic calculation is:
ASSETS − LIABILITIES = NET WORTH
For example:
Assets: $450,000
Liabilities: $300,000
Net worth: $150,000
It’s a simple calculation.
But what it represents can be much more meaningful.
Because your net worth gives you a view of your financial life that your paycheque simply can’t.
Income tells you what you earn. Net worth tells you what you're building.
Imagine you receive a pay rise.
Your income increases.
That’s great.
But what happens next?
You could use the additional money to increase your lifestyle.
Or you could direct some of it towards savings, debt reduction, investments or other long-term financial priorities.
The first decision increases what you can spend.
The second can potentially strengthen what you own relative to what you owe.
This is why net worth can change the way you think about money.
Instead of asking:
“How much can I afford?”
You may start asking:
“What can this money help me build?”
That is a completely different financial perspective.
Your net worth gives your money a bigger picture
Budgeting usually focuses on your money flow.
Money comes in.
Money goes out.
You allocate what remains.
Net worth adds another layer.
It asks:
“What is happening to my overall financial position?”
You might discover that:
Your income has increased, but so has your debt.
Your spending has increased, but your savings haven’t.
Your savings are growing.
Your mortgage balance is gradually falling.
Your superannuation is increasing over time.
Your investments have grown, or fallen in value.
Your financial position is changing even when your monthly budget looks relatively similar.
That bigger picture matters.
Because financial progress isn’t always visible from your bank balance.
Net worth turns money into a long-term conversation
One of the most powerful things about tracking net worth is that it moves your attention from today to over time.
Your monthly budget might tell you:
“I have $2,000 left after my expenses.”
Your net worth asks:
“What is my financial position compared with six months ago?”
Or:
“Am I gradually building financial strength?”
Or even:
“Are my financial decisions moving me towards the future I want?”
This doesn’t mean your net worth needs to increase every single month.
Markets move.
Property values change.
Debt fluctuates.
Life happens.
What matters is the longer-term direction.
Think of your net worth less like a grade and more like a compass.
It’s there to help you understand where you are.
A growing net worth can change what “success” looks like
We are constantly surrounded by visible measures of financial success.
The home.
The car.
The holiday.
The wardrobe.
The restaurant.
The lifestyle.
But some of the most important financial progress is invisible.
It might look like:
$5,000 sitting in savings.
A debt balance gradually decreasing.
A growing superannuation balance.
An investment portfolio being built over time.
A mortgage becoming smaller relative to the value of the property.
A growing financial buffer.
Nobody necessarily sees these things.
But they matter.
This is one of the reasons I love the idea of quiet wealth.
You don’t have to look wealthy to be becoming wealthier.
Your financial progress doesn’t need an audience.
Net worth can make you think differently about spending
This is where things get really interesting.
Tracking net worth doesn’t mean you suddenly have to stop spending.
It isn’t about becoming obsessed with saving.
It’s about becoming more aware of the relationship between spending today and building tomorrow.
You might start asking:
“Is this purchase worth the money I’m giving it?”
“Does this actually improve my life?”
“Would I rather put this money towards something else?”
“Am I spending because I genuinely value this, or because I’m trying to keep up?”
That doesn’t mean the answer is always “don’t buy it.”
Sometimes the answer is absolutely:
“Yes. This is worth it.”
That’s intentional spending.
The goal isn’t to spend as little as possible.
It’s to become more deliberate about where your money goes.
Your net worth can help you see the cost of lifestyle inflation
Lifestyle inflation is one of those things that can happen quietly.
You earn more.
You spend more.
You upgrade.
You earn more again.
You upgrade again.
Eventually, your higher income doesn’t necessarily translate into greater financial freedom.
Your lifestyle simply becomes more expensive.
Tracking net worth can interrupt that cycle.
Because instead of asking:
“How much more can I spend?”
you can ask:
“How much more financial strength can I create?”
Maybe your next pay rise funds a better lifestyle.
Maybe part of it does.
And maybe part of it builds your future.
There is no universal percentage that works for everyone.
The important thing is creating a deliberate relationship between income growth and wealth growth.
Net worth can make financial goals feel more connected
Sometimes financial goals can feel like separate projects.
Save for a holiday.
Pay off the credit card.
Build an emergency fund.
Save for a home.
Invest.
Increase super contributions.
Build retirement savings.
But when you track your net worth, you can start seeing how these decisions connect.
Reducing debt can strengthen your financial position.
Building savings can increase your assets.
Building investments can increase your ownership of financial assets, although their values can rise and fall.
Making consistent contributions towards long-term goals can create momentum.
Suddenly, your money isn’t a collection of unrelated tasks.
It’s becoming a financial strategy.
Your net worth isn't a measure of your worth
This deserves its own section.
Because money numbers can become emotional very quickly.
Your net worth is information.
It is not your identity.
It does not tell you whether you’re successful.
It doesn’t tell you whether you’re “behind.”
It doesn’t measure your intelligence.
It doesn’t measure your happiness.
And it certainly doesn’t determine your value as a person.
Your net worth can be negative.
It can be small.
It can fluctuate.
It can grow slowly.
And it can change dramatically throughout your life.
The point of tracking it isn’t to judge yourself.
It’s to understand yourself.
Clarity, not comparison.
A negative net worth doesn't mean you're failing
This is particularly important if you’re just starting to pay attention to your finances.
You may look at your assets and liabilities and discover that you owe more than you own.
That can feel confronting.
But it can also be the beginning of a completely different financial chapter.
Instead of avoiding the number, you now know where you’re starting.
And that’s powerful.
Because you can’t create a financial strategy around numbers you don’t know.
Your first net worth calculation isn’t supposed to impress you.
It’s supposed to inform you.
Your net worth can reveal financial blind spots
Sometimes we think we’re doing well financially because our income feels comfortable.
But your net worth can tell a different story.
Perhaps your income is high but your debt is also high.
Perhaps you have significant assets but very little accessible savings.
Perhaps you’re saving regularly but haven’t started thinking about your longer-term financial position.
Perhaps your spending has increased faster than your income.
Perhaps you’re building wealth quietly without realising how much progress you’ve actually made.
The number doesn’t necessarily tell you what to do.
But it can tell you where to look.
And that’s valuable.
How to start tracking your net worth
You don’t need a complicated financial system.
Start simple.
STEP 1 – LIST YOUR ASSETS
Write down the current value of your major assets.
For example:
- Savings
- Investments
- Superannuation
- Property
- Other relevant assets
STEP 2 – LIST YOUR LIABILITIES
Write down what you currently owe.
For example:
- Mortgage
- Personal loans
- Car finance
- Credit cards
- Other debts
STEP 3 – DO THE MATH
Subtract your total liabilities from your total assets.
Assets − Liabilities = Net Worth
STEP 4 – RECORD YOUR STARTING POINT
Don’t judge the number.
Record it.
This is your baseline.
STEP 5 – CHECK IT PERIODICALLY
You don’t need to obsess over it.
A monthly or quarterly check-in can be enough for many people.
The goal is to see the bigger picture over time, not react emotionally to every movement.
Don't just track the number. Track the story.
This is where net worth becomes much more useful.
Imagine your net worth changes from:
$42,000 → $48,000 → $56,000 → $63,000
The numbers are interesting.
But the story behind them is even more valuable.
Maybe you:
Built an emergency fund.
Paid down debt.
Increased your savings rate.
Started investing.
Received a pay rise and avoided lifestyle inflation.
Built more financial structure.
Stayed consistent.
That story tells you something about your financial habits.
And that’s where the real value of tracking net worth lies.
The Finance Strategy Co. Net Worth Reset™
Set aside 30 minutes for a simple financial check-in.
5 MINUTES – KNOW
Write down your:
Assets + Liabilities + Net Worth
Don’t overthink it.
5 MINUTES – COMPARE
If you have previous numbers, compare them.
Ask:
What’s changed?
What’s improved?
What has moved backwards?
No judgement.
Just information.
5 MINUTES – UNDERSTAND
Ask:
What caused the change?
Was it:
- Saving?
- Debt reduction?
- Spending?
- Investment movements?
- A major purchase?
- A change in income?
- Something else?
5 MINUTES – REFLECT
Ask yourself:
What financial behaviour am I proud of?
Where could I become more intentional?
What financial habit is worth continuing?
5 MINUTES – CHOOSE ONE MOVE
Pick one action that strengthens your financial strategy.
Perhaps:
Save.
Organise.
Reduce debt.
Review spending.
Increase financial margin.
Learn.
Plan.
Keep it simple.
FINAL MINUTES – LOOK FORWARD
Complete this sentence:
“By this time next year, I would love my financial position to…”
Don’t create a fantasy number.
Create an intentional direction.
The Finance Strategy Method™
Net worth fits beautifully into the five-part Finance Strategy Method™:
KNOW
Know what you own.
Know what you owe.
Know your starting point.
Clarity comes first.
ORGANISE
Bring your accounts, debts, savings and financial information into one system.
Organisation creates visibility.
PLAN
Decide what you want your money to accomplish.
Direction creates intention.
BUILD
Strengthen your savings, manage debt and build assets according to your goals and circumstances.
Consistency creates momentum.
THRIVE
Use your financial strength to create more choice, flexibility and opportunities in your life.
Wealth is ultimately about what your money makes possible.
Your net worth is a snapshot, not a prediction
It’s important not to become too attached to the number.
Your net worth can change for many reasons.
Investment values move.
Property values change.
Debt gets paid down.
Major purchases happen.
Life changes.
Income changes.
Your financial priorities evolve.
So don’t treat your net worth like a stock price you need to watch every day.
Think of it as a financial photograph.
Every so often, you take another picture.
Then you step back and look at the collection.
Where have I been?
Where am I now?
Where am I heading?
That’s much more useful than obsessing over one particular number.
Wealth is more than a number
Your net worth matters.
But it isn’t the whole story.
You can have a growing net worth and still feel stressed about money.
You can have a modest net worth and be building a strong financial foundation.
You can have financial goals that matter more to you than a particular number.
And you can define wealth differently from everyone around you.
Maybe wealth means:
Having choices.
Having financial breathing room.
Being able to take time off.
Owning your home.
Travelling.
Supporting your family.
Building a business.
Creating flexibility.
Retiring comfortably.
Having fewer financial worries.
Being able to say yes to opportunities.
Being able to say no without fear.
That’s why net worth should be a tool for perspective, not another number to obsess over.
The quiet power of knowing your number
There is something incredibly grounding about knowing where you stand.
Not because the number makes you better.
Not because it makes you successful.
Not because it tells you whether you’ve “made it.”
But because you know.
You know what you own.
You know what you owe.
You know what’s changing.
You know what you’re building.
And when you know, you can make better-informed decisions.
That is the real power of financial organisation.
Your money. Your perspective. Your future.
Your income tells part of your story.
Your spending tells another.
Your savings reveal what you’re preparing for.
Your debt tells you what you’re carrying.
And your net worth gives you a broader view of the financial picture.
But ultimately, the number isn’t the destination.
It’s a tool.
A tool that can help you move from short-term thinking to long-term strategy.
From consumption to intention.
From comparison to clarity.
From “How much can I spend?” to “What am I building?”
And perhaps most importantly:
From simply managing your money…
to intentionally creating a financial life that supports the life you want.
Because wealth doesn’t need to be loud.
It doesn’t need to be displayed.
It doesn’t need to be compared.
Sometimes, wealth is simply the quiet confidence of knowing that you’re building something stronger, one intentional financial decision at a time.
Your money. Your strategy. Your future.
Finance Strategy Co.
Money, but make it intentional.
Ready to Take Control of Your Money?
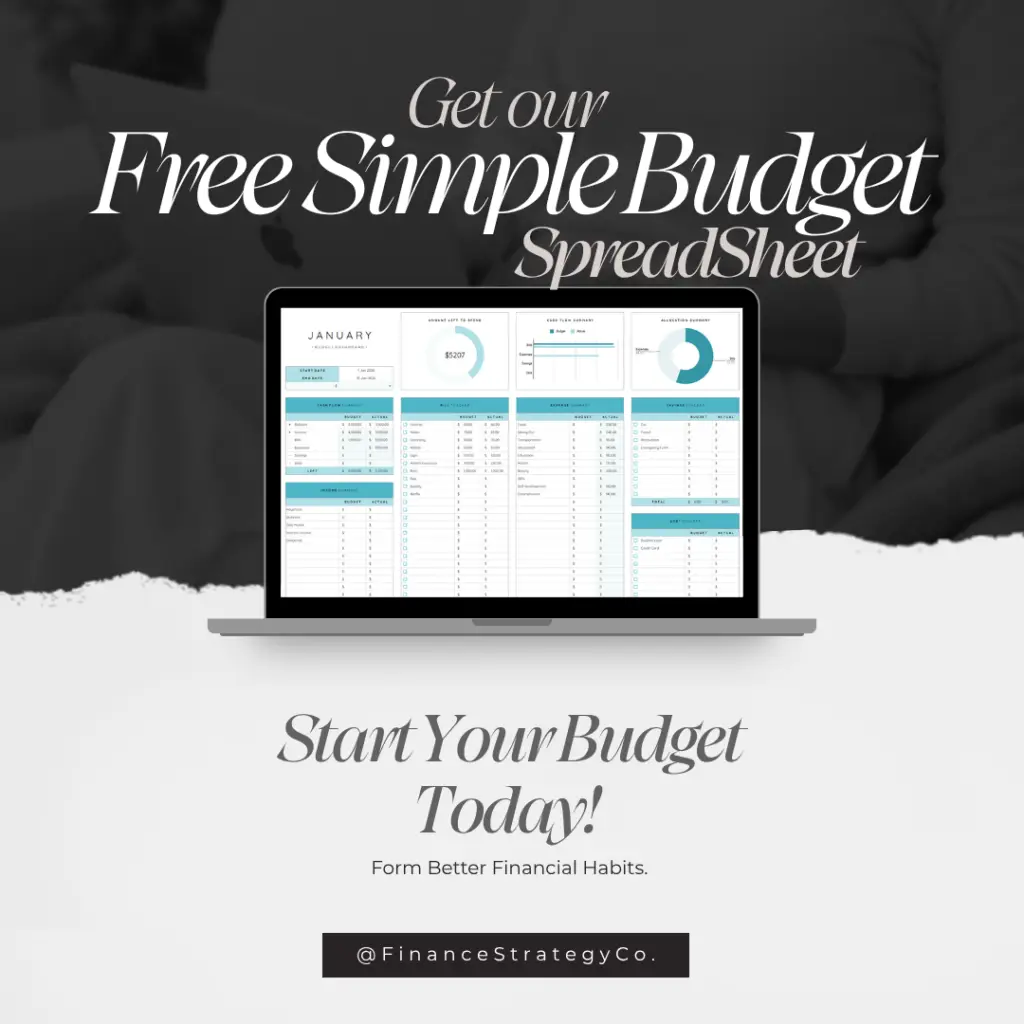
Finance Strategy Co. creates thoughtfully designed financial tools to help you organise your money, track your debt, plan your goals and build a financial strategy around the life you actually want.
Money management, elevated.