
There is something exciting about setting a financial goal.
A goal tells you where you want to go. A money strategy tells your money how to get you there.
There is something exciting about setting a financial goal.
A holiday you’ve always wanted to take.
A home deposit.
A healthier emergency fund.
Paying off debt.
Building wealth.
Creating more freedom in your life.
We often think the hard part is deciding what we want.
But having the goal is only the beginning.
The real transformation happens when you take that goal and turn it into a money strategy.
Because “I want to save more” is a goal.
“I will save $400 each month, automatically transfer it on payday, reduce spending in three areas and review my progress at the end of every month” is a strategy.
That distinction matters.
A goal gives your money a destination.
A strategy gives it direction.
And when the two work together, your financial life starts to feel much more intentional.
A Goal Is the Destination. Your Strategy Is the Roadmap.
Let’s say you have a goal to save $10,000.
That’s a clear target.
But the number alone doesn’t tell you:
- how much you need to save
- when you need the money
- where the money will come from
- which expenses may need to change
- where you’ll keep the savings
- how often you’ll check your progress
- what you’ll do if your circumstances change
This is where strategy comes in.
A financial strategy connects your income, spending, saving, priorities and goals so that your everyday financial decisions are moving you towards something meaningful.
A budget tells you what is happening.
A goal tells you what you want.
A strategy connects the two.
Start With What You Actually Want
Before you open a spreadsheet or start cutting expenses, step back.
Ask yourself:
What am I actually trying to create?
Not just:
“How much do I want to save?”
But:
“What will this money make possible?”
Perhaps you’re saving $20,000 for a home deposit.
The real goal might be:
I want more stability and a place that feels like my own.
Perhaps you’re building a $5,000 emergency fund.
The deeper goal might be:
I want to feel prepared instead of financially vulnerable.
Perhaps you’re investing for the future.
The bigger goal might be:
I want to create more choices for my future self.
The number matters.
But the meaning behind the number matters too.
When you understand the why, it becomes much easier to build a strategy around the goal.
01 - Define the Goal Clearly
Vague goals are difficult to build strategies around.
“Save more money” isn’t a strategy-ready goal.
Instead, make your goal specific.
Think about:
WHAT
What are you trying to achieve?
HOW MUCH
What amount do you need?
WHEN
When would you ideally like to achieve it?
WHY
Why does this matter to you?
PRIORITY
How important is this goal compared with everything else you’re working towards?
For example:
Goal: Build a $10,000 travel fund
Why: Take a three-week European holiday
Target date: June 2027
Amount needed: $10,000
Priority: High
Strategy: Save approximately $850 per month
Suddenly, the goal feels different.
It has direction.
02 - Work Backwards From the Goal
This is where your goal becomes a strategy.
Instead of asking:
“How much can I save?”
Start with:
“What do I need to do to reach this?”
The basic calculation is simple:
Goal amount ÷ number of saving periods = required contribution
For example:
$10,000 ÷ 12 months = approximately $833 per month
That number gives you something incredibly valuable:
clarity.
You can now ask whether $833 per month is realistic.
If it is, you’ve created your starting point.
If it isn’t, that doesn’t mean the goal has failed.
It means your strategy needs adjusting.
You might:
- extend the timeline
- reduce the target
- increase income
- reduce selected expenses
- redirect existing savings
- combine several approaches
A strategy should respond to reality.
It shouldn’t require you to pretend your financial life is different from what it actually is.
03 - Look at Your Current Money Picture
You cannot create a realistic strategy without knowing your starting point.
Before deciding what needs to change, understand:
Income
What comes in?
Essential expenses
What has to be paid?
Flexible spending
Where do you have choices?
Debt
What do you owe and what repayments are required?
Savings
What do you already have?
Investments
What are you currently building for the future?
Existing goals
What are you already saving towards?
Available cash flow
What is realistically left after your commitments?
A budget can help you see this clearly.
Current Moneysmart guidance recommends recording income and expenses, comparing money coming in with money going out, setting savings goals and reviewing the budget as circumstances change.
Your strategy should be built from your real numbers, not your ideal numbers.
04 - Give Your Money a Job
One of the simplest ways to create financial direction is to stop thinking about your money as one big pool.
Instead, give different amounts different purposes.
For example:
LIVE
Money for your everyday life.
Rent or mortgage, groceries, transport, utilities and other essentials.
ENJOY
Money for the lifestyle you want today.
Dining out, hobbies, experiences, beauty, entertainment and fun.
PROTECT
Money that creates financial security.
Emergency savings, insurance and other forms of financial protection.
PLAN
Money for your upcoming goals.
Travel, a home deposit, education, a car or other meaningful purchases.
BUILD
Money directed towards longer-term wealth building.
Depending on your circumstances, this may include investing, superannuation or reducing debt.
The exact categories will look different for everyone.
The important thing is that your money has purpose.
05 - Choose Your Financial Priorities
You may have ten goals.
That doesn’t mean all ten need equal attention.
Trying to save for everything at once can create a financial strategy that looks impressive on paper but feels impossible in real life.
Instead, ask:
What matters most right now?
You might choose:
ONE PRIMARY GOAL
Your main focus.
ONE PROTECTION GOAL
Something that strengthens your financial foundation.
ONE LONG-TERM GOAL
Something that supports your future.
For example:
Primary: Save $8,000 for a home deposit
Protection: Build emergency savings
Long-term: Contribute consistently towards investing
Your priorities can change.
That’s okay.
A financial strategy is not a permanent contract.
It’s a framework that evolves with your life.
06 - Turn the Goal Into a Monthly Number
This is where the strategy becomes practical.
Let’s say your goal is:
$6,000 in 12 months
Your target becomes:
$500 per month
Or:
approximately $115 per week
Now ask:
Where will that $500 come from?
Maybe:
$300 → existing monthly surplus
$100 → reduced discretionary spending
$50 → automatic transfer
$50 → additional income
Suddenly you’re no longer simply hoping to save $6,000.
You’ve created a plan for how the money will be found.
This is the difference between a financial wish and a financial strategy.
07 - Build the Strategy Into Your Routine
The best strategy isn’t the most complicated one.
It’s the one you can actually follow.
If your plan requires you to remember twelve different transfers every month, manually track every transaction and constantly recalculate your goals, it may not survive a busy month.
Look for opportunities to automate.
For example:
Payday → bills → savings → spending → future goals
You can set up regular transfers into savings so that your goal is funded automatically.
Moneysmart currently recommends automatic transfers, separate savings accounts and tracking progress as ways to make saving more consistent.
The principle is simple:
Make the right financial behaviour easier to repeat.
You decide once.
Your system keeps going.
08 - Create Milestones
Large financial goals can feel distant.
Break them down.
Instead of thinking:
“I need to save $10,000.”
Think:
$1,000
↓
$2,500
↓
$5,000
↓
$7,500
↓
$10,000
Every milestone becomes evidence that your strategy is working.
This is especially useful for long-term goals.
Progress doesn’t always feel dramatic.
Sometimes it looks like another $100 transferred into savings.
Another month of staying within your spending plan.
Another debt payment.
Another contribution towards your future.
Small actions become significant when they are repeated.
09 - Build Flexibility Into the Plan
One of the biggest mistakes people make with financial goals is creating strategies that only work when everything goes perfectly.
But life doesn’t work that way.
Your income may change.
Your expenses may increase.
An unexpected cost may appear.
Your priorities may shift.
You may simply decide that the goal isn’t as important as it once was.
That doesn’t mean your strategy has failed.
It means it’s time for a review.
Moneysmart recommends reviewing savings goals and adjusting contributions or timelines when income, expenses or priorities change.
Think of your strategy as something you refine, not something you either pass or fail.
10 - Create Your “If Things Change” Plan
A sophisticated financial strategy includes a Plan B.
Ask yourself:
What happens if my income decreases?
What happens if my expenses increase?
What happens if I need to use my savings?
What happens if I can’t meet my monthly target?
Your answer might be:
- reduce the contribution temporarily
- extend the deadline
- pause a lower-priority goal
- reduce discretionary spending
- redirect an upcoming windfall
- rebuild your emergency savings first
- review the entire strategy
This gives you something incredibly valuable:
permission to adapt without abandoning the goal.
Don't Confuse Sacrifice With Strategy
There is a common belief that achieving financial goals requires saying no to everything.
It doesn’t.
A strong money strategy shouldn’t make your life miserable in the name of a future you may not even recognise when you get there.
You still need:
- enjoyment
- rest
- experiences
- flexibility
- connection
- things that make your life feel like yours
The goal isn’t to eliminate everything enjoyable.
The goal is to understand what matters enough to fund.
This is where intentional spending becomes part of your financial strategy.
You don’t necessarily need to spend less everywhere.
You may simply need to spend more intentionally.
Your Money Strategy Should Reflect Your Life
Imagine two people earning exactly the same income.
One prioritises travel.
The other prioritises buying a home.
One wants to work less in the future.
The other wants to build a business.
One values experiences.
The other values financial security.
Their money strategies should look different.
There is no universal financial blueprint.
Your strategy should reflect:
your income
your responsibilities
your priorities
your values
your timeline
your lifestyle
your future
That’s what makes it personal.
The Finance Strategy Method™
At Finance Strategy Co., we believe your money works best when it has direction.
That’s why our approach follows five simple stages:
KNOW
Understand your numbers.
What comes in?
What goes out?
What do you own?
What do you owe?
ORGANISE
Create structure.
Accounts.
Bills.
Expenses.
Subscriptions.
Savings.
PLAN
Give your money direction.
Goals.
Priorities.
Timelines.
Strategies.
BUILD
Take consistent action.
Save.
Reduce debt.
Build financial resilience.
Grow your wealth over time.
THRIVE
Use your money to support the life you’re actually building.
More freedom.
More choices.
More confidence.
More intention.
KNOW → ORGANISE → PLAN → BUILD → THRIVE
That’s the Finance Strategy Method™.
Your 30-Minute Money Strategy Reset
You don’t need an entire weekend to begin.
Set aside 30 minutes.
Put your phone away.
Open your banking app, budget or financial spreadsheet.
Then work through these questions.
1. What am I working towards?
Write down your most important financial goal.
2. Why does it matter?
Write the reason behind it.
3. How much do I need?
Choose a specific number.
4. When do I want to reach it?
Choose a realistic timeframe.
5. How much do I need to save?
Calculate your weekly, fortnightly or monthly contribution.
6. Where will the money come from?
Look at your current cash flow.
7. What needs to change?
Identify one to three realistic adjustments.
8. What can I automate?
Set up transfers where appropriate.
9. What milestone comes first?
Choose your first checkpoint.
10. When will I review the strategy?
Put a date in your calendar.
That’s it.
You now have the beginning of a money strategy.
When Your Goal Feels Too Big
Sometimes the number feels overwhelming.
You look at a $20,000 goal and think:
“There’s no way.”
Don’t immediately abandon it.
Break it down.
$20,000 sounds very different when you look at it as:
$1,667 per month
or approximately:
$385 per week.
Then ask a better question:
“What would need to happen for this to become possible?”
Perhaps the answer is a longer timeframe.
Perhaps it’s a combination of saving and increasing income.
Perhaps another goal needs to come first.
Perhaps your original target needs to change.
The purpose of breaking a goal down isn’t to convince yourself that everything is possible.
It’s to make the numbers visible enough to make an informed decision.
When Your Goal Feels Too Small
The opposite can happen too.
You might think:
“I’m only saving $50 a week. It’s not enough to matter.”
It matters.
A consistent strategy doesn’t become insignificant because the starting amount is small.
Moneysmart notes that even small, regular savings can add up over time, while also emphasising that your savings plan should be realistic and sustainable.
Your first goal isn’t necessarily to create a perfect financial life.
It’s to create a system you can continue.
Then improve it.
The Most Important Question to Ask
Whenever you set a financial goal, ask:
“What does my money need to do for this goal to become possible?”
That question changes everything.
It moves you from:
I want to save.
to:
I need to allocate $400 each month.
From:
I want to travel.
to:
I need a dedicated travel fund with an automatic contribution.
From:
I want to build wealth.
to:
I need a long-term plan that considers my goals, timeframe and financial position.
The goal becomes specific.
The money gets a job.
The strategy becomes visible.
And your daily decisions start connecting to something bigger.
Your Goals Don't Need More Pressure. They Need a Plan.
You don’t need to completely overhaul your financial life every time you set a new goal.
You need clarity.
You need priorities.
You need realistic numbers.
You need systems that make progress easier.
And you need the flexibility to adjust when life changes.
Your money strategy isn’t about controlling every dollar.
It’s about directing your money towards what matters most.
Because financial progress isn’t created by having the perfect goal.
It’s created by knowing where you’re going, and consistently giving your money a role in getting you there.
That’s the real power of a money strategy.
Not restriction.
Not perfection.
Direction.
And when your money has direction, your goals stop feeling like distant ideas.
They become something you’re actively building.
Your Money. Your Strategy. Your Future.
At Finance Strategy Co., we believe your financial life should support the life you’re creating, not compete with it.
Your goals are personal.
Your priorities are personal.
And your strategy should be personal too.
Know your money.
Organise your money.
Plan your future.
Build with intention.
Thrive on your terms.
Your money. Your strategy. Your future.
Ready to Elevate Your Money Management?
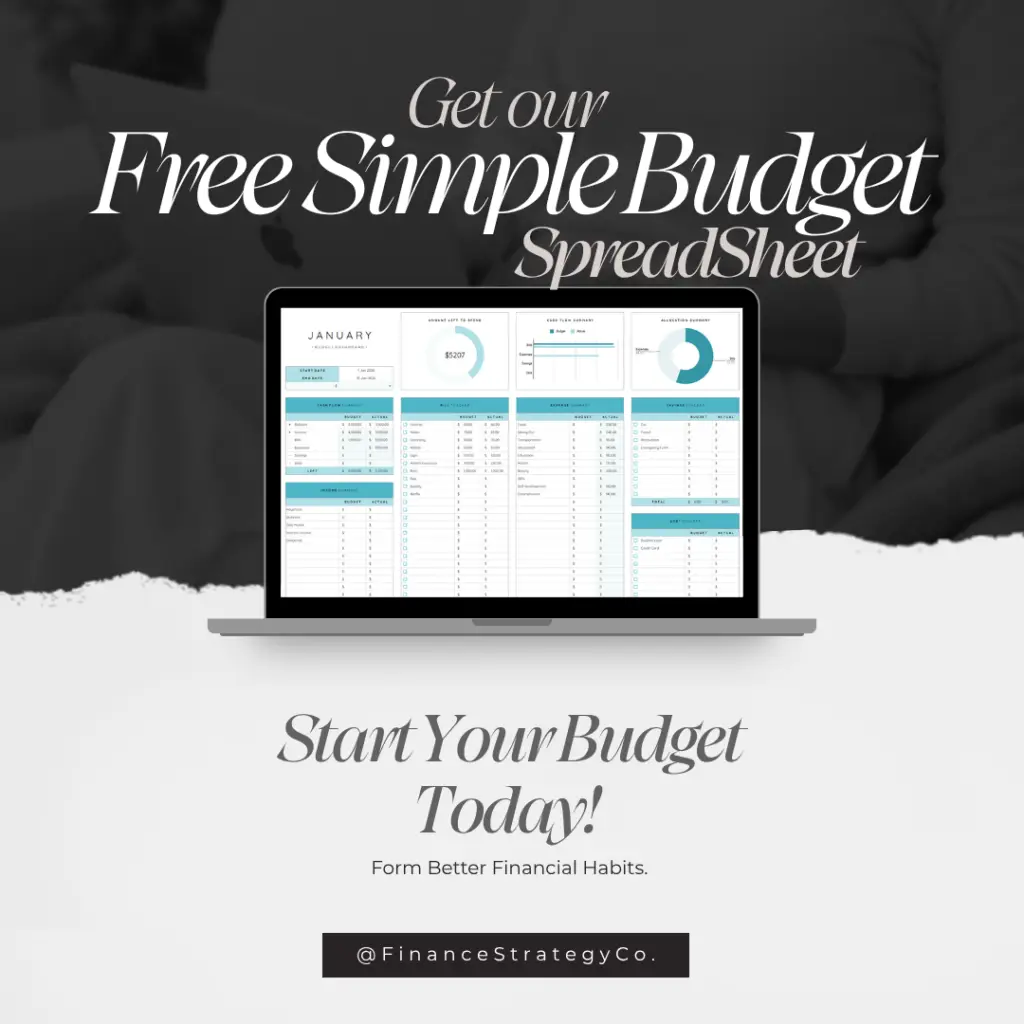
Finance Strategy Co. creates thoughtfully designed financial tools to help you organise your money, plan ahead, track your progress and build a financial system that fits your life.
Money management, elevated.