
approach to creating a calmer, clearer financial life, without overcomplicating your money.
There is a certain kind of freedom that comes from simplicity.
Knowing what you have.
Knowing what you owe.
Knowing what needs to be paid.
Knowing what you’re saving for.
And knowing that your financial system actually works.
Yet somewhere along the way, managing money became complicated.
Multiple accounts.
Endless subscriptions.
Bills arriving at different times.
Budgets with dozens of categories.
Savings goals scattered across different places.
Spreadsheets that take longer to maintain than they do to help.
And suddenly, managing your money becomes a job in itself.
But your finances don’t need to be complicated to be effective.
In fact, the best financial system may be the simplest one you can consistently maintain.
Simplifying your finances isn’t about caring less about your money.
It’s about removing the unnecessary so you can focus on what actually matters.
Welcome to a simpler way of managing your money.
What Does It Mean to Simplify Your Finances?
Financial simplicity means creating a money system that is:
Clear.
Intentional.
Easy to maintain.
Aligned with your priorities.
Flexible enough for real life.
It means knowing where your money is going without needing to constantly monitor every transaction.
It means having systems for bills, spending, saving and financial goals.
It means reducing financial clutter.
And perhaps most importantly, it means creating a system that doesn’t make you dread managing your money.
Your finances should support your life.
They shouldn’t consume it.
Tracking spending is one of the simplest places to start because it gives you visibility into where your money is actually going and can help reveal recurring costs, spending patterns and opportunities to make changes.
The Finance Strategy Approach
At Finance Strategy Co., we believe financial organisation should create clarity, not complexity.
That’s why our approach follows the:
KNOW → ORGANISE → PLAN → BUILD → THRIVE
You don’t need more financial rules.
You need a system that makes sense for you.
So let’s simplify it.
01 - Start With Your Financial Snapshot
Before you simplify anything, you need to understand what you’re working with.
Think of this as your financial reset button.
Take a moment to list:
Money coming in
- Salary or wages
- Business income
- Freelance income
- Government payments
- Investment income
- Other regular income
Money going out
- Housing
- Utilities
- Groceries
- Transport
- Insurance
- Debt repayments
- Subscriptions
- Lifestyle spending
- Irregular expenses
Money you’re building
- Emergency savings
- Short-term savings
- Long-term savings
- Investments
- Other financial goals
Don’t make changes yet.
Just look.
A realistic financial picture should include both regular and less frequent expenses, which is why reviewing several months of transactions can be useful.
You can’t simplify what you haven’t understood.
02 - Reduce the Number of Places Your Money Lives
Open your banking app.
How many accounts do you have?
And more importantly:
Do you know why you have each one?
Having multiple accounts isn’t necessarily a problem.
But having accounts with no clear purpose can create unnecessary complexity.
Consider giving each account a specific role.
For example:
Everyday
Your regular spending.
Bills
Your recurring financial commitments.
Savings
Your short- and medium-term goals.
Future
Longer-term financial goals and wealth building.
You don’t need to copy someone else’s bank account system.
The goal is simply to make your own system easier to understand.
A useful question is:
If I looked at my accounts today, would I immediately know what each one is for?
If the answer is no, that’s an opportunity to simplify.
03 - Create Fewer, Better Budget Categories
One of the easiest ways to make budgeting unnecessarily complicated is to create too many categories.
Do you really need separate categories for:
- coffee
- takeaway
- restaurants
- lunch
- snacks
- groceries
- food delivery?
Maybe.
But probably not.
Your budget should give you useful information without requiring you to become an accountant.
Consider broader categories such as:
HOME
FOOD
TRANSPORT
HEALTH
PERSONAL
LIFESTYLE
DEBT
SAVINGS
FUTURE
You can always make your categories more detailed if you need to.
But start simple.
A budget is meant to be a practical plan for your money, not a second full-time job. Current Moneysmart guidance similarly recommends keeping a clear record of income and expenses and reviewing the budget as circumstances change.
04 - Give Every Recurring Expense a Home
Bills feel complicated when they’re scattered.
One bill comes from your email.
Another is direct debited from your everyday account.
Another comes quarterly.
Another annually.
And somewhere in between, a subscription quietly renews.
Let’s change that.
Create one central Recurring Expenses List.
| Expense | Amount | Frequency | Due Date |
|---|---|---|---|
| Rent/Mortgage | $ | Weekly/Monthly | |
| Electricity | $ | Monthly/Quarterly | |
| Insurance | $ | Monthly/Annual | |
| Internet | $ | Monthly | |
| Phone | $ | Monthly | |
| Subscriptions | $ | Monthly/Annual |
Now you have one place to look.
You can also create a bill calendar so you can see when expenses are due throughout the month.
The objective isn’t to control every detail.
It’s simply to remove the element of surprise.
05 - Audit Your Subscriptions
Subscriptions are one of the easiest forms of financial clutter.
They’re small.
They’re automatic.
And because they’re recurring, they can easily disappear into the background.
Take 15 minutes to review them.
Ask:
Do I use this?
Do I enjoy it?
Does it make my life easier?
Is it still worth the cost?
Would I sign up for it today?
If the answer is no, cancel it.
If the answer is yes, keep it.
This isn’t about cutting everything that isn’t essential.
It’s about making sure your recurring spending still reflects your current life.
06 - Create One Place to Track Your Spending
You don’t need five different systems.
Choose one.
It could be:
- a Google Sheet
- a budgeting app
- your banking app
- an expense tracker
- a notebook
The tool isn’t the important part.
Consistency is.
Tracking your spending can help you identify patterns and forgotten costs, including unused subscriptions and small purchases that add up over time.
Choose the system you’ll actually use.
Because the most sophisticated financial tracker in the world isn’t helpful if you never open it.
07 - Automate the Boring Stuff
Some parts of managing money don’t need your attention every week.
Bills.
Savings.
Regular transfers.
Certain debt repayments.
Where appropriate, automate them.
For example:
PAYDAY
↓
Income arrives
↓
Bills allocation
↓
Savings transfer
↓
Financial goals
↓
Everyday spending
Automation can reduce the number of financial decisions you have to make manually.
Regular transfers can also make saving easier to maintain as a habit.
But automation should never mean set and forget forever.
Review your automated payments occasionally to make sure they’re still appropriate.
08 - Create a System for Irregular Expenses
Here’s where many budgets become complicated.
The problem isn’t necessarily the budget.
It’s the fact that life doesn’t happen neatly every month.
Car registration.
Insurance renewals.
Birthdays.
Christmas.
Annual memberships.
Home repairs.
Travel.
Medical expenses.
These aren’t monthly expenses, but they still need funding.
Instead of allowing them to become financial surprises, create sinking funds.
For example:
CAR
Registration, servicing and repairs.
HOME
Maintenance and unexpected household costs.
TRAVEL
Upcoming holidays and experiences.
GIFTS
Birthdays, Christmas and celebrations.
ANNUAL
Expenses that occur once or twice a year.
Then contribute regularly.
You’re not making your finances more complicated.
You’re making future expenses easier to manage.
09 - Simplify Your Savings Goals
You don’t need twenty savings goals.
You need goals that matter.
Instead of having separate accounts for every little thing, consider grouping your goals.
For example:
SECURITY
Emergency fund and financial buffer.
EXPERIENCES
Travel, holidays and meaningful experiences.
LIFE
Home, car or other major purchases.
FUTURE
Long-term financial goals.
The names don’t matter.
The purpose does.
When your savings have meaning, it becomes easier to understand why you’re putting money aside.
Moneysmart also recommends identifying what you’re saving for and creating a simple plan around the amount and timeframe.
10 - Simplify Your Financial Paperwork
Financial clutter isn’t only digital.
It can also be physical.
Old statements.
Bills.
Receipts.
Insurance documents.
Tax records.
Investment information.
Create one secure digital filing system.
You might use folders such as:
BANKING
BILLS
INSURANCE
TAX
DEBT
INVESTMENTS
PROPERTY
PERSONAL
The goal is simple:
If you need a document, you know where it is.
Just remember to protect sensitive financial information appropriately and avoid storing important documents in unsecured locations.
11 - Stop Managing Your Money Every Day
This might sound strange.
But simplifying your finances means you shouldn’t need to constantly think about them.
Instead, create a rhythm.
Weekly
10–15 minutes
Check:
- balances
- recent spending
- upcoming bills
- budget progress
Monthly
30–45 minutes
Review:
- income
- expenses
- savings
- debt
- subscriptions
- financial goals
Quarterly
60–90 minutes
Step back and review:
- your overall financial position
- goals
- spending patterns
- savings progress
- debt
- net worth
- lifestyle priorities
A regular review rhythm helps prevent small issues from becoming overwhelming ones.
And it means your finances don’t need your attention every single day.
12 - Know Your Financial Numbers
You don’t need to memorise every transaction.
But there are a few numbers you should know.
Your monthly income
What comes in?
Your essential expenses
What must be paid?
Your average lifestyle spending
What does your life actually cost?
Your savings rate
How much are you putting toward future goals?
Your debt balances
What do you owe?
Your net worth
What do you own compared with what you owe?
These numbers create your financial dashboard.
You don’t need to obsess over them.
You simply need to know where you stand.
13 - Eliminate Financial Decisions You Don't Need to Make
Financial complexity often comes from too many decisions.
Where should this money go?
Which account should pay this bill?
How much should I save this month?
When should I transfer the money?
What category does this expense belong to?
A good financial system answers these questions before you need to ask them.
For example:
Payday → savings transfer
Payday → bills allocation
Weekly → spending check
Monthly → financial review
Quarterly → financial reset
The more decisions your system can make simple, the less mental energy you need to spend managing your money.
14. Give Your Money Fewer Jobs, But Better Jobs
Every dollar doesn’t need a complicated story.
Instead, think in terms of priorities.
TODAY
The money required for your current life.
SECURITY
Money that protects you from unexpected expenses.
GOALS
Money for the things you’re actively working toward.
FUTURE
Money supporting your longer-term financial direction.
This creates a simple framework for thinking about your money without creating endless categories.
Your money has a purpose.
Your system simply helps you see it.
15 - Remove What No Longer Serves You
Simplifying your finances isn’t just about adding better systems.
It’s also about removing things.
Remove:
Unused subscriptions.
Unnecessary accounts.
Duplicate services.
Complicated spreadsheets.
Financial habits you no longer need.
Goals that no longer matter.
Categories that create more work than clarity.
Processes that make managing money harder than it needs to be.
Your financial system should evolve with your life.
Something that worked beautifully two years ago might not make sense today.
That’s okay.
Simplification is an ongoing process.
Your Simple Financial System
If you want to strip everything back, start here.
ONE
One primary budgeting system.
TWO
A small number of clearly defined bank accounts.
THREE
One recurring-expenses list.
FOUR
One spending tracker.
FIVE
A few meaningful savings goals.
SIX
Automated transfers where appropriate.
SEVEN
A weekly, monthly and quarterly money routine.
That’s it.
You don’t need a complicated financial ecosystem.
You need a system you understand.
The 30-Minute Finance Simplify Reset
Want to start today?
Set a timer for 30 minutes.
MINUTES 1–5
Open your bank accounts.
Write down what each account is currently used for.
MINUTES 6–10
Review your subscriptions.
Identify anything you no longer use.
MINUTES 11–15
Review your upcoming bills.
Make sure you know what is due next.
MINUTES 16–20
Look at your recent spending.
Identify one pattern you want to understand better.
MINUTES 21–25
Review your savings goals.
Are they still relevant?
MINUTES 26–30
Choose one thing to simplify.
Cancel.
Combine.
Automate.
Rename.
Reorganise.
Or remove.
One change is enough.
The Beauty of a Financial System That Just Works
Imagine opening your banking app and understanding what you’re looking at.
Imagine knowing your bills are accounted for.
Imagine your savings happening automatically.
Imagine knowing what you’re working toward.
Imagine no longer wondering where your money went every month.
That is the beauty of financial simplicity.
Not having fewer dollars.
Not spending less for the sake of spending less.
But having less financial noise.
Simplify Your Finances, Not Your Life
This is where we believe financial advice often gets it wrong.
Simplifying your finances shouldn’t mean simplifying your life.
You can still travel.
You can still enjoy restaurants.
You can still buy beautiful things.
You can still spend money on experiences.
You can still have fun.
The goal is not to create a life where every purchase requires guilt or calculation.
The goal is to create a financial system that allows you to spend intentionally on the things you genuinely value.
Simplicity should create more freedom, not less.
The Finance Strategy Method™
At Finance Strategy Co., we believe your financial system should ultimately move you through five stages:
KNOW
Understand your financial reality.
ORGANISE
Remove clutter and create structure.
PLAN
Give your money direction.
BUILD
Strengthen your financial foundation and work toward your goals.
THRIVE
Use your money to create more choice, confidence and freedom.
Because financial organisation isn’t the destination.
It’s the foundation.
Final Thoughts
Your finances don’t need to be complicated to be successful.
You don’t need dozens of categories.
You don’t need endless spreadsheets.
You don’t need to check your bank account ten times a day.
And you certainly don’t need to become perfect with money.
You need clarity.
You need intention.
You need a system that fits your life.
Start by understanding your numbers.
Then remove the clutter.
Create simple systems.
Automate what makes sense.
Give your money clear priorities.
And review your system regularly.
Because sometimes the most powerful financial change isn’t adding something new.
It’s deciding what you no longer need.
Simplify your money.
Create more clarity.
Make space for what matters.
And build a financial life that feels as good as it looks on paper.
Your money. Your strategy. Your future.
Ready to Make Your Money Feel More Organised?
Your budget is easier to maintain when your financial system is simple.
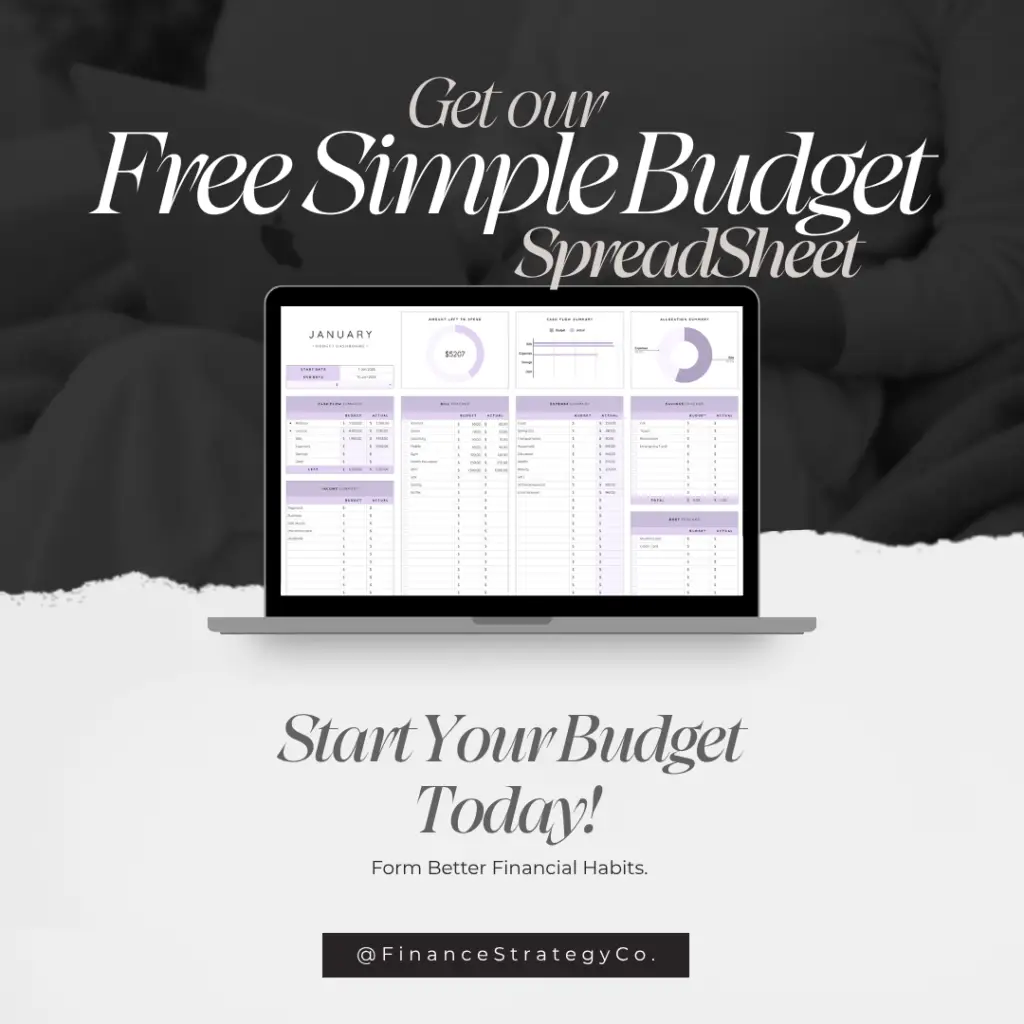
Explore Finance Strategy Co.'s thoughtfully designed budgeting and financial organisation tools to help you plan your spending, track your expenses, manage your goals and create a financial system that fits your life.
Your money deserves a strategy.