
Stop saving whatever is left over. Give your savings a strategy.
Saving money sounds simple.
Spend less.
Save more.
Repeat.
But if it were really that easy, most people wouldn’t struggle to build meaningful savings.
The problem isn’t always a lack of discipline.
Sometimes, it’s a lack of strategy.
You may know you want to save more, but without a clear purpose, savings can become whatever happens to be left at the end of the month.
And when life gets busy, there may be nothing left at all.
At Finance Strategy Co., we believe saving should be intentional.
Your money should have direction.
Your goals should have a plan.
And your savings strategy should support the life you’re actually trying to create.
Because saving isn’t about depriving yourself today.
It’s about giving your future more options.
What Is a Savings Strategy?
A savings strategy is a structured plan for what you’re saving for, how much you want to save, where your savings will go and how you’ll stay on track.
Instead of having one vague goal:
“I need to save more.”
You create a system.
You might be saving for:
- An emergency fund
- A holiday
- A home deposit
- A new car
- Christmas
- Annual expenses
- A major purchase
- A career break
- A business
- Future financial security
- Long-term goals
Each goal can have a purpose, target and timeframe.
That’s the difference between saving and strategic saving.
Why You Need a Savings Strategy
Without a strategy, saving can feel like an endless cycle.
You save.
You spend.
You save again.
You never quite know whether you’re making progress.
A savings strategy gives your money a destination.
Instead of asking:
“How much should I save?”
You can ask:
“What am I building towards?”
That question changes everything.
When your savings represent something meaningful, it becomes easier to make intentional decisions about your spending.
You aren’t simply saying no to something.
You’re saying yes to something that matters more.
The Finance Strategy Method™
At Finance Strategy Co., we believe your financial strategy can be built around five simple stages:
KNOW → ORGANISE → PLAN → BUILD → THRIVE
Saving sits primarily within the PLAN and BUILD stages.
KNOW
Understand your current financial position.
ORGANISE
Create structure around your money.
PLAN
Decide what you’re saving for and when you want to achieve it.
BUILD
Consistently contribute towards your goals.
THRIVE
Use your financial progress to create more freedom and flexibility in your life.
Your savings strategy isn’t isolated from the rest of your finances.
It is part of the bigger picture.
01 - Know Why You're Saving
Before you choose a savings target, identify your reason.
This may seem simple, but it is one of the most important steps.
Ask yourself:
What am I saving for?
Why does it matter to me?
What will this money make possible?
How will I feel when I reach the goal?
Your reason doesn’t have to be impressive.
It could be:
Feeling financially secure.
Taking your dream holiday.
Buying your first home.
Having more flexibility.
Being prepared for unexpected expenses.
Creating a better future for your family.
Give your savings an emotional purpose.
A number is easier to work towards when it represents something you genuinely care about.
02 - Create Separate Savings Goals
Instead of putting every savings goal into one large bucket, consider giving each goal its own purpose.
For example:
EMERGENCY
Your financial safety net.
HOME
A future property deposit or home-related goal.
TRAVEL
Your next holiday or travel experience.
CAR
A future vehicle purchase or vehicle-related expenses.
CHRISTMAS
Gifts, celebrations and end-of-year expenses.
ANNUAL EXPENSES
Predictable costs that don’t occur every month.
FUTURE
Longer-term financial goals.
The exact categories will depend on your lifestyle.
The goal is clarity.
When you can see exactly what you’re saving for, your progress becomes tangible.
03 - Separate Emergency Savings From Goal Savings
This is an important distinction.
Your emergency fund and your other savings goals serve different purposes.
Emergency Fund
Designed for unexpected and necessary expenses or financial disruptions.
Goal Savings
Designed for planned purchases and lifestyle goals.
For example:
Your car registration is due every year.
That’s predictable.
It could be appropriate to save towards it through a sinking fund.
Your car unexpectedly needs a major repair.
That’s different.
Your emergency fund may be designed to help with situations like this.
Plan for what you know.
Protect yourself from what you don’t.
04 - Set a Specific Savings Target
Now give your goal a number.
Instead of:
“I want to save for a holiday.”
Try:
“I want to save $4,000 for my holiday.”
Then give it a timeframe.
For example:
Goal: $4,000
Deadline: 12 months
Now your goal becomes measurable.
You can calculate the contribution required based on your chosen timeframe and payment frequency.
The important thing is to make the target realistic.
A sustainable savings strategy will always beat an unrealistic one.
05 - Break the Goal Into Smaller Milestones
Large numbers can feel intimidating.
Instead of focusing on the final destination, break the goal into smaller milestones.
For example:
$500
$1,000
$1,500
$2,000
$3,000
$4,000
Each milestone gives you something to celebrate.
You don’t need to wait until you reach the final number before recognising your progress.
Small wins create momentum.
06 - Decide How Much You Can Save
Now look at your actual financial life.
Review your income and expenses.
Then ask:
What can I realistically save each payday?
Your answer might be:
$25
$50
$100
$250
Or another amount that works for you.
Don’t choose an amount because it sounds impressive.
Choose one you can maintain.
If your income varies, you might prefer to use a percentage or set a minimum amount and save more during stronger income periods.
Your savings strategy needs to work on an ordinary month, not just your best month.
07 - Pay Yourself First
One of the simplest ways to make saving more consistent is to prioritise it.
Instead of waiting until the end of the month to see what’s left, consider moving your planned savings amount when you receive your income.
For example:
Income arrives → Savings transfer → Bills → Everyday spending
The exact order will depend on your circumstances and financial obligations.
The principle is simply:
Make saving intentional rather than accidental.
08 - Automate Your Savings
Automation can remove a huge amount of friction from the saving process.
You can set up regular transfers into appropriate savings accounts or goal-based savings spaces.
For example:
Every payday
$100 → Emergency Fund
$75 → Holiday Fund
$50 → Home Fund
The amounts will depend entirely on your goals and circumstances.
But once automated, your savings strategy doesn’t require you to remember to make the transfer every time.
Your financial system should help you succeed on the days when motivation is nowhere to be found.
09 - Create a Sinking Fund Strategy
Not every savings goal is a traditional savings goal.
Some expenses are predictable but irregular.
These are perfect candidates for sinking funds.
Think:
- Car registration
- Insurance
- Christmas
- Birthdays
- School expenses
- Home maintenance
- Annual memberships
- Professional expenses
- Holidays
Instead of waiting for the expense to arrive, estimate the annual cost and gradually set money aside.
For example:
If an annual expense is approximately $1,200, you could divide that amount across the number of pay periods you have available.
The expense hasn’t disappeared.
You’ve simply prepared for it.
10 - Find Your Savings Opportunities
Building a savings strategy doesn’t mean cutting everything you enjoy.
Instead, look for places where your money isn’t delivering enough value.
Review:
Subscriptions
Are you still using them?
Recurring expenses
Could any be reduced?
Impulse spending
Are there purchases you regularly regret?
Convenience spending
Which purchases genuinely save you time or improve your life?
Lifestyle spending
Are you spending intentionally on the things you value most?
The objective isn’t to make your life smaller.
It’s to make your spending more intentional.
11 - Use Windfalls Strategically
Extra money can create an opportunity to accelerate your savings.
This could include:
- Bonuses
- Tax refunds
- Gifts
- Side income
- Money from selling unwanted items
- Other unexpected income
You don’t need to save every dollar.
Enjoying some of your money is part of a healthy financial life.
But you might decide on a personal rule.
For example:
50% Future
30% Goals
20% Enjoyment
Your percentages can be completely different.
The important thing is to decide before the money arrives.
Give unexpected money a strategy too.
12 - Make Saving Part of Your Lifestyle
Saving shouldn’t feel like a punishment.
If your strategy requires you to eliminate every coffee, cancel every dinner and never enjoy yourself, it probably won’t be sustainable.
Instead, build saving into your lifestyle.
You might decide:
I save automatically every payday.
I plan my larger purchases.
I have a dedicated travel fund.
I set aside money for annual expenses.
I review my savings once a week.
I increase my savings when my income increases.
These habits become part of how you live.
Saving becomes a lifestyle rather than a temporary challenge.
13 - Protect Your Savings From Lifestyle Creep
As your income increases, it can be tempting for your spending to increase at exactly the same rate.
A pay rise becomes:
A bigger house.
A nicer car.
More subscriptions.
More dining out.
More shopping.
More lifestyle expenses.
There is nothing inherently wrong with enjoying increased income.
But consider giving some of every income increase a future purpose.
For example:
When my income increases, I will direct a portion towards savings before increasing my lifestyle spending.
This allows your lifestyle to improve while your financial position improves too.
Earn more.
Enjoy more.
Build more.
14 - Track Your Savings Progress
What gets measured becomes easier to see.
Create a simple savings tracker.
For each goal, record:
Goal
Target amount
Current balance
Amount remaining
Deadline
Progress percentage
For example:
HOLIDAY
Target: $5,000
Saved: $3,250
Remaining: $1,750
Progress: 65%
Seeing that percentage move can be incredibly motivating.
Your savings tracker should remind you how far you’ve come.
15 - Have a Weekly Money Reset
Your savings strategy doesn’t need to take hours.
Use your Sunday Money Reset™ to check in with your savings.
Take five minutes to ask:
Did I save what I planned?
Are my savings goals still realistic?
Do I have any upcoming expenses?
Do I need to adjust anything?
What is my next milestone?
This keeps your savings strategy connected to your everyday financial life.
What If You Can't Save Much Right Now?
This is important.
Not everyone has significant disposable income.
If your budget is already stretched, don’t compare your savings journey to someone else’s.
Start where you are.
Perhaps your first goal is:
$100
Then:
$250
Then:
$500
You may need to focus on increasing income, reducing essential expenses where possible or stabilising your financial position before saving aggressively.
There is no minimum amount that makes saving worthwhile.
The habit matters.
How to Create a Savings Strategy on a Low Income
If you’re working with a smaller income, your strategy may need to be different.
Focus on:
Small automatic contributions
Even a small regular amount creates consistency.
Specific goals
Prioritise the savings goal that matters most right now.
Reducing financial leaks
Review subscriptions and recurring expenses.
Windfalls
Direct a portion of unexpected money towards savings.
Income growth
Where possible, look for sustainable ways to increase income.
Milestones
Celebrate progress rather than focusing only on the final number.
Your strategy doesn’t need to look impressive.
It needs to work for you.
Your Savings Strategy Should Support Your Life
One of the biggest mistakes people make is treating saving as the opposite of enjoying life.
It isn’t.
You can save for your future while enjoying your present.
You can build financial security while travelling.
You can work towards a home while enjoying dinner with friends.
You can build an emergency fund while spending money on things you genuinely value.
The answer isn’t restriction.
It’s intention.
When your money has a strategy, you can make conscious decisions about what deserves your money today and what deserves it tomorrow.
The Luxury of Financial Preparedness
There is a quiet confidence that comes from having money set aside.
You don’t need to constantly worry about what’s next.
You have prepared.
You don’t need to rely on motivation every payday.
Your system is working.
You don’t need to feel guilty when you spend money on something meaningful.
You’ve already accounted for it.
That’s the luxury of a savings strategy.
Not simply having more money.
Having options.
Your Money Deserves a Plan
Saving isn’t about putting every spare dollar into an account and hoping that one day you’ll have enough.
It’s about knowing what you’re building.
Create goals that matter.
Give each goal a purpose.
Choose realistic targets.
Automate your contributions.
Track your progress.
Adjust when life changes.
And celebrate the milestones along the way.
KNOW.
Understand where you are.
ORGANISE.
Create structure around your money.
PLAN.
Decide what you’re saving for.
BUILD.
Consistently work towards your goals.
THRIVE.
Use your financial progress to create more freedom, flexibility and choice.
That’s the Finance Strategy Co. approach.
Because your savings shouldn’t simply sit in an account without direction.
Your savings should be part of a bigger strategy for the life you’re creating.
Ready to Build Your Savings Strategy?
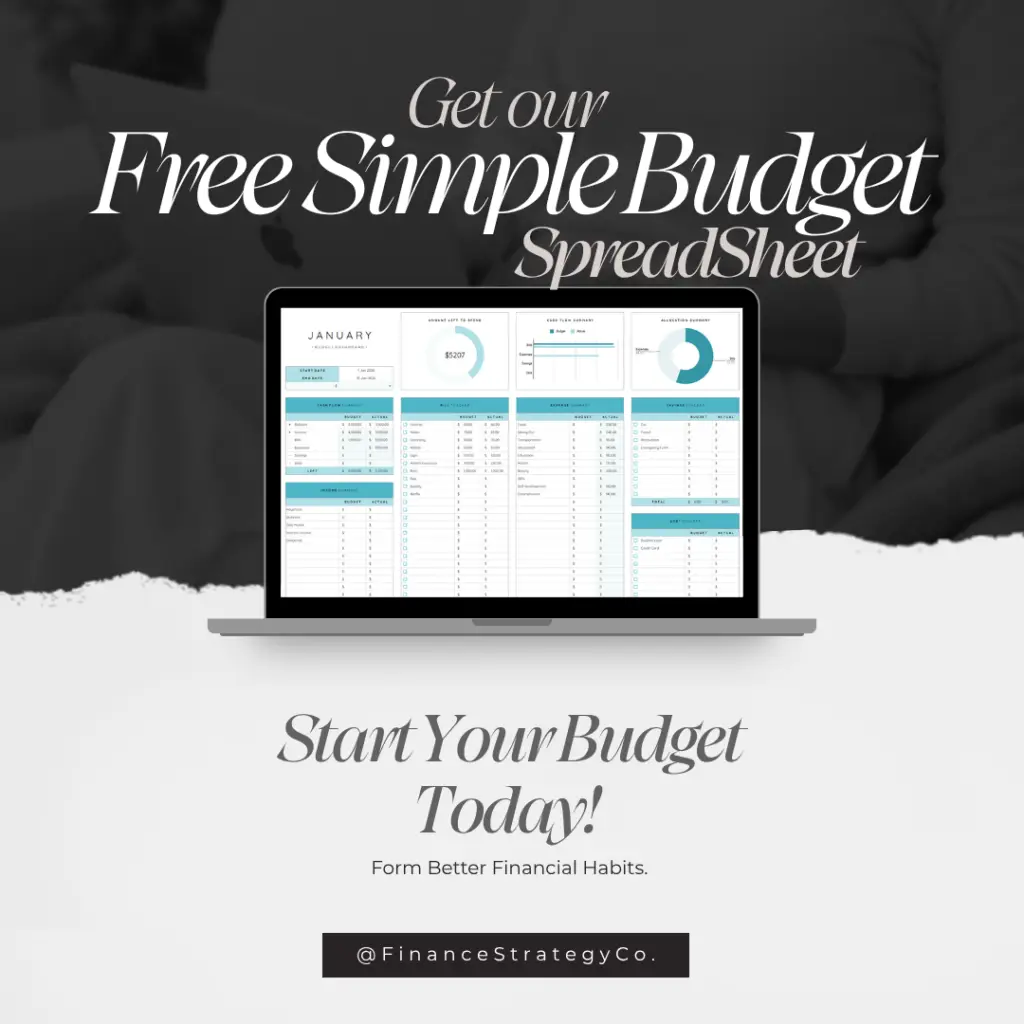
The right tools can make your savings goals easier to organise, track and achieve.
Explore the Finance Strategy Co. collection of thoughtfully designed budgeting, savings and financial planning tools created to help you turn financial intentions into organised, actionable strategies.
Money management, elevated.