
Five years can feel both incredibly far away and surprisingly close.
Your future doesn't need to be perfectly predicted. It needs to be intentionally planned.
Think about where you were five years ago.
Your income may have changed.
Your priorities may have changed.
Your lifestyle may have changed.
You may have started or ended a relationship, changed careers, moved homes, started a family or simply realised that you wanted something different from your life.
And that’s exactly why a five-year financial plan isn’t about predicting the future.
It’s about giving your future direction.
A five-year plan gives you a bigger picture of where you want your money to take you—and then helps you work backwards into the decisions, habits and systems that can move you there.
It turns:
“I want my finances to be better.”
into:
“This is what I’m building, this is why it matters, and this is what my money needs to do over the next five years.”
That is the difference between having financial goals and having a financial strategy.
What Is a Five-Year Financial Plan?
A five-year financial plan is a roadmap for your money over the next five years.
It brings together your:
- financial goals
- income
- spending
- savings
- debt
- emergency fund
- major purchases
- lifestyle priorities
- investments
- wealth-building goals
- financial milestones
The purpose isn’t to create a rigid five-year budget.
Your day-to-day budget will change.
Your income may change.
Your priorities may change.
Your life will change.
Instead, your five-year plan acts as your financial compass.
It helps you answer:
Where am I going, and what does my money need to do to help me get there?
Australian Government’s Moneysmart recommends defining financial goals by how much you need and how long you have to achieve them, with goals commonly considered across short-, medium- and long-term timeframes. A five-year horizon sits at the intersection of medium- and longer-term planning, depending on the goal.
Why Create a Five-Year Financial Plan?
You don’t need a five-year plan because you need to control every detail of your future.
You create one because clarity creates better decisions.
Without a plan, it’s easy to:
Save without knowing what you’re saving for.
Spend without thinking about the bigger picture.
Set goals that compete with each other.
Move from one financial priority to another.
Put off important decisions.
Focus only on what’s happening this month.
A five-year plan gives your money a longer view.
Instead of asking:
“Can I afford this?”
you can also ask:
“Does this support where I’m trying to go?”
That’s a much more powerful financial question.
Start With the Life You Want
Before you look at spreadsheets, savings rates or numbers, start somewhere more important:
Your life.
Imagine it’s five years from now.
What does a great financial life look like?
Where do you live?
What does your work look like?
What does your lifestyle feel like?
What do you have more freedom to do?
What financial pressure would you love to have removed?
What are you proud of building?
Maybe your five-year vision includes:
- owning a home
- travelling more
- becoming debt-free
- building an emergency fund
- growing your savings
- investing consistently
- increasing your income
- starting a business
- changing careers
- working fewer hours
- building more financial security
- having more freedom
- creating a lifestyle you genuinely enjoy
Your financial plan should support your life.
Not the other way around.
Your Five-Year Financial Vision
Take a moment and complete this sentence:
“In five years, I want my financial life to feel…”
Maybe your answer is:
Secure.
Free.
Organised.
Abundant.
Calm.
Flexible.
Independent.
Prepared.
There is no right answer.
This isn’t about choosing the most impressive financial goal.
It’s about defining what financial success means to you.
Because your five-year plan should be built around your definition of a good life.
01 - Take Your Financial Snapshot
Before deciding where you’re going, understand where you’re starting.
Create a simple financial snapshot.
Record:
INCOME
What comes into your household?
EXPENSES
What does it cost to live your current life?
SAVINGS
How much do you currently have saved?
DEBT
What do you currently owe?
ASSETS
What do you own?
This may include savings, investments, property and superannuation.
NET WORTH
Your assets minus your liabilities.
MONTHLY CASH FLOW
How much money remains after your regular expenses?
This information gives you your starting point.
Moneysmart recommends reviewing income, expenses, debts and assets when developing a financial or investing plan, because understanding your current position helps you determine what you can realistically put towards future goals.
And remember:
Your starting point is information, not a judgement.
There is no shame in starting exactly where you are.
02 - Choose Your Five-Year Goals
Now decide what you want to accomplish.
Try not to create a list of twenty goals.
Instead, choose the goals that would make the biggest difference to your life.
You might choose goals from different areas.
SECURITY
Build an emergency fund.
DEBT
Pay down high-interest debt.
SAVINGS
Build a specific savings balance.
LIFESTYLE
Save for travel, a home, education or another major life goal.
WEALTH
Increase long-term investments or superannuation contributions.
INCOME
Increase your earning potential.
FREEDOM
Create more financial flexibility.
Your plan doesn’t need every category.
Choose what matters to you.
03 - Separate Your Goals by Timeframe
Not every goal needs to happen in five years.
Some goals need attention immediately.
Others will take years.
A simple way to organise them is:
NOW
The next 12 months.
BUILD
Years two and three.
EXPAND
Years four and five.
For example:
YEAR 1
Build a $5,000 emergency fund.
Pay down credit card debt.
Create a consistent monthly budget.
YEARS 2–3
Increase savings.
Save for a home deposit.
Increase income.
Begin or increase long-term investing.
YEARS 4–5
Reach your deposit target.
Strengthen your investment strategy.
Increase financial flexibility.
Prepare for the next stage of life.
The exact timeline will depend on your circumstances.
The point is to create a sequence.
04 - Turn Every Goal Into a Number
This is where your vision becomes a financial plan.
Instead of:
“I want to build savings.”
Choose:
“I want $15,000 saved by December 2031.”
Instead of:
“I want to pay off debt.”
Choose:
“I want to reduce my debt by $12,000 over the next two years.”
Instead of:
“I want to invest more.”
Choose:
“I want to contribute a consistent amount towards my long-term investment goal.”
Specific numbers give you something to work with.
They allow you to calculate:
How much?
By when?
How often?
From where?
Moneysmart similarly recommends defining financial goals by the amount required and the timeframe for reaching them.
05 - Work Backwards
Now take each major goal and work backwards.
Imagine your five-year goal is:
$30,000
You have five years.
That’s 60 months.
$30,000 ÷ 60 = $500 per month
Your goal has now become a contribution.
And that contribution becomes part of your monthly money strategy.
You can then ask:
Can my current cash flow support $500 per month?
If yes, fantastic.
If not, you have options.
You could:
- extend the timeline
- adjust the target
- reduce selected expenses
- increase income
- redirect existing savings
- pause a lower-priority goal
- combine several approaches
The numbers aren’t there to tell you that your goal is impossible.
They’re there to show you what the goal requires.
06 - Create Your Five-Year Financial Priorities
This is one of the most important parts of the process.
Because you may want everything.
But your money has limits.
You might want to:
Save for a home.
Travel.
Invest.
Pay off debt.
Upgrade your car.
Build an emergency fund.
Start a business.
Renovate your home.
Increase your lifestyle.
All at once.
The answer isn’t necessarily to give up your goals.
It’s to sequence them.
Ask:
What needs to happen first?
What will protect my financial foundation?
Which goal has the closest deadline?
Which goal matters most to me?
Which goals can happen at the same time?
Which goals need to wait?
Your financial strategy becomes much more powerful when your goals stop competing and start working together.
07 - Build Your Financial Foundation First
Before focusing heavily on long-term goals, make sure the foundation underneath them is strong.
This can include:
A realistic budget
A cash-flow system
Emergency savings
Debt management
Appropriate insurance
Organised accounts
Regular savings
A system for upcoming expenses
This doesn’t mean every person needs to complete every item before moving forward.
Life isn’t that linear.
But a strong foundation can make your longer-term plan more resilient.
Moneysmart’s current budgeting guidance recommends understanding income and expenses, including irregular costs, setting savings goals and reviewing your budget as circumstances change.
08 - Give Your Goals Their Own Money
One of the simplest ways to make a five-year plan feel real is to give each major goal a place in your financial system.
Instead of one vague savings account called:
Savings
you might have:
Emergency Fund
Home Deposit
Travel
Future
Investing
The exact structure is completely personal.
But naming your money creates clarity.
It lets you see what you’re actually building.
And there’s something motivating about watching a goal move from:
$0 → $1,000 → $5,000 → $10,000
Your money stops feeling abstract.
It starts becoming tangible progress.
09 - Build Your Plan Into Your Budget
Your five-year plan shouldn’t live in a beautiful spreadsheet that you open once a year.
It needs to connect to your everyday money.
Your monthly budget is where the five-year strategy becomes action.
For example:
Income
↓
Essentials
↓
Financial commitments
↓
Savings goals
↓
Debt reduction
↓
Long-term wealth building
↓
Lifestyle spending
The exact order will depend on your circumstances.
The important part is that your monthly money decisions should support your larger financial direction.
Moneysmart describes a budget as a money plan that helps you understand money coming in and going out, manage spending and save for things that matter.
Think of it this way:
Your five-year plan is the destination.
Your annual plan is the route.
Your monthly budget is the next step.
10 - Create Annual Milestones
Five years can feel overwhelming.
Five years is also made up of:
5 years
60 months
260-ish weeks
thousands of small financial decisions
You don’t need to achieve the entire plan today.
Break it into annual milestones.
YEAR ONE
What must happen this year?
YEAR TWO
What should be stronger by the end of year two?
YEAR THREE
What should you be building?
YEAR FOUR
What should be within reach?
YEAR FIVE
What would success look like?
For example:
| Year | Focus |
|---|---|
| Year 1 | Organise & stabilise |
| Year 2 | Strengthen |
| Year 3 | Build |
| Year 4 | Expand |
| Year 5 | Thrive |
This gives your five-year vision structure without making it feel overwhelming.
11 - Create Your “Money Moves”
For each year, decide what actions actually need to happen.
For example:
YEAR ONE
- create a realistic budget
- organise financial accounts
- build emergency savings
- review subscriptions
- create sinking funds
- establish regular savings
- reduce high-priority debt
YEAR TWO
- increase savings rate
- review insurance and recurring expenses
- increase income where possible
- strengthen financial systems
- review investment strategy if appropriate
YEAR THREE
- increase long-term contributions
- review major financial goals
- reassess lifestyle spending
- update your financial roadmap
YEAR FOUR
- accelerate priority goals
- strengthen wealth-building strategy
- prepare for major upcoming expenses
YEAR FIVE
- review what you’ve built
- celebrate progress
- reassess your next five years
- create your next financial strategy
These actions turn your plan from an idea into a system.
12 - Don't Forget Your Income
Financial planning isn’t only about reducing spending.
There is a limit to how much you can optimise expenses.
Income, however, can potentially grow.
Your five-year plan should therefore include the question:
“How might I increase my financial capacity?”
That might mean:
- negotiating a salary increase
- developing new skills
- changing roles
- starting a side business
- increasing business revenue
- developing additional income streams
- pursuing professional qualifications
You don’t need to chase constant productivity.
The goal is not:
Earn more. Spend more.
It’s:
Earn more. Create more options.
Additional income can give you more capacity to save, invest, reduce debt or fund the lifestyle you want.
13 - Include Your Lifestyle Goals
A financial plan shouldn’t only contain serious financial goals.
Your life is happening while you’re building your future.
So include the things you actually want to experience.
Maybe you want:
A European summer.
A beautiful home.
More weekends away.
A career change.
More time with your family.
A year of travel.
A business of your own.
More flexibility.
These goals belong in your financial plan too.
Because money is not the destination.
It’s the tool that helps make your life possible.
14 - Think About Wealth, Not Just Savings
A five-year plan can also be the point where you start thinking beyond simply accumulating cash.
Depending on your circumstances, you may want to consider longer-term wealth-building strategies.
These might include:
- superannuation
- diversified investments
- reducing debt
- growing your income
- building business assets
- increasing your savings capacity
If you’re considering investing, your timeframe and risk tolerance matter. Moneysmart recommends matching investments to your goals, timeframe and comfort with risk, and reviewing the plan regularly.
A five-year plan doesn’t mean you need to invest.
It means you should understand which of your goals require saving, which may involve investing, and which require other strategies.
15 - Create Your Financial “Why”
Your five-year plan will be much easier to follow when it has emotional meaning.
Don’t just write:
$50,000 savings goal.
Write:
“$50,000 gives me the foundation for the next chapter of my life.”
Don’t just write:
Debt-free.
Write:
“Being debt-free gives me more flexibility and less financial pressure.”
Don’t just write:
Invest consistently.
Write:
“I’m building future options for myself.”
Your numbers tell you what you’re doing.
Your why reminds you why it matters.
The Five-Year Financial Review
Your five-year plan isn’t something you create and forget.
Set a regular review rhythm.
MONTHLY
Review your budget and progress.
QUARTERLY
Look at your goals and spending patterns.
ANNUALLY
Complete a deeper financial review.
Ask:
What changed?
What did I achieve?
What no longer matters?
What became more important?
Am I still on track?
What needs to change?
Moneysmart recommends reviewing budgets as income, expenses and goals change, while its investing guidance recommends reviewing investment plans regularly to ensure they remain aligned with goals, timeframe and risk tolerance.
This is why your plan should be flexible enough to evolve.
What If Your Five-Year Plan Changes?
It probably will.
And that’s okay.
Your five-year plan is not a promise to your future self that nothing will change.
It’s a starting point.
Maybe you planned to buy a home and later decided you don’t want one.
Maybe you planned to travel and then decided you’d rather build a business.
Maybe your income increases significantly.
Maybe your circumstances change.
Maybe a completely different opportunity appears.
You don’t need to stay loyal to an outdated plan simply because you wrote it down.
Update the strategy.
Your goals are allowed to evolve.
Your money strategy should evolve with them.
The 80/20 Approach to Your Five-Year Plan
You don’t need to predict everything.
Focus on the financial decisions that are likely to have the biggest impact.
For example:
Know your numbers.
Control your cash flow.
Build financial resilience.
Prioritise meaningful goals.
Automate good financial habits.
Manage debt intentionally.
Increase your financial capacity.
Build long-term wealth where appropriate.
Review your plan regularly.
These principles can remain useful even when the details change.
Your Five-Year Plan Doesn't Need to Be Perfect
There is a temptation to make a financial plan incredibly detailed.
Five-year projections.
Perfect savings targets.
Precise investment returns.
Exact income predictions.
Detailed spending assumptions.
But the further into the future you go, the more uncertain the details become.
Your five-year plan doesn’t need false precision.
It needs clear direction.
You don’t need to know exactly what your life will look like in five years.
You need to know:
What matters to me?
What am I building?
What financial foundation do I need?
What should I focus on first?
What actions can I take now?
That’s enough to begin.
The Finance Strategy Method™
At Finance Strategy Co., we believe financial planning should feel less like predicting the future and more like intentionally building it.
That’s why our approach follows:
KNOW
Understand where you are.
Your income.
Your expenses.
Your savings.
Your debt.
Your assets.
Your priorities.
ORGANISE
Create the systems that support your plan.
Your accounts.
Your bills.
Your budget.
Your savings.
Your financial routines.
PLAN
Give your money direction.
Your five-year vision.
Your goals.
Your milestones.
Your priorities.
Your roadmap.
BUILD
Take consistent action.
Save.
Reduce debt.
Increase financial capacity.
Build wealth.
Strengthen your financial foundation.
THRIVE
Use the progress you’ve created to build a life with more choice, confidence and freedom.
KNOW → ORGANISE → PLAN → BUILD → THRIVE
Your financial plan is not about becoming obsessed with money.
It’s about giving your money a purpose.
Your 30-Minute Five-Year Financial Vision
If creating an entire five-year plan feels overwhelming, start here.
Set a timer for 30 minutes.
MINUTES 1–5: DREAM
Write down what you want your life to look and feel like five years from now.
Don’t think about whether it’s possible yet.
Just write.
MINUTES 6–10: DEFINE
Choose your five most important financial goals.
MINUTES 11–15: QUANTIFY
Give each goal a number and timeframe.
MINUTES 16–20: PRIORITISE
Decide what needs to happen first.
MINUTES 21–25: STRATEGISE
Write down the monthly or annual actions required.
MINUTES 26–30: COMMIT
Choose your first three actions.
Then stop.
You don’t need to build your entire future in one afternoon.
You simply need to decide what you’re building.
The Quiet Power of Having a Financial Plan
There is something powerful about knowing where you’re going.
Not because the future is guaranteed.
But because you’re no longer leaving every financial decision to chance.
You know what you’re working towards.
You know what matters.
You know what your money is being asked to do.
And when an opportunity, purchase or financial decision appears, you have something to measure it against.
Does this support the life I’m building?
That question can change the way you spend, save and plan.
It can make financial decisions feel less emotional.
Less reactive.
Less overwhelming.
More intentional.
That is the quiet power of a financial strategy.
Your Future Doesn't Need More Pressure. It Needs Direction.
A five-year financial plan isn’t about becoming a completely different person.
It’s about becoming more intentional with the person you already are.
You don’t need to know exactly where you’ll be five years from now.
You simply need to decide what matters enough to start building today.
Start with your vision.
Turn it into goals.
Turn the goals into numbers.
Turn the numbers into priorities.
Turn the priorities into systems.
Then give those systems time to work.
Five years from now, you’ll still be living your life.
The question is:
What do you want your money to have made possible by then?
Because the future you’re imagining doesn’t begin five years from now.
It begins with the decisions you make today.
Your Money. Your Strategy. Your Future.
At Finance Strategy Co., we believe financial planning isn’t about restriction, perfection or predicting every detail of your future.
It’s about creating a financial life that supports the life you actually want.
Know your money.
Organise your money.
Plan your future.
Build with intention.
Thrive on your terms.
Your future is worth planning for.
Your money. Your strategy. Your future.
Ready to Elevate Your Money Management?
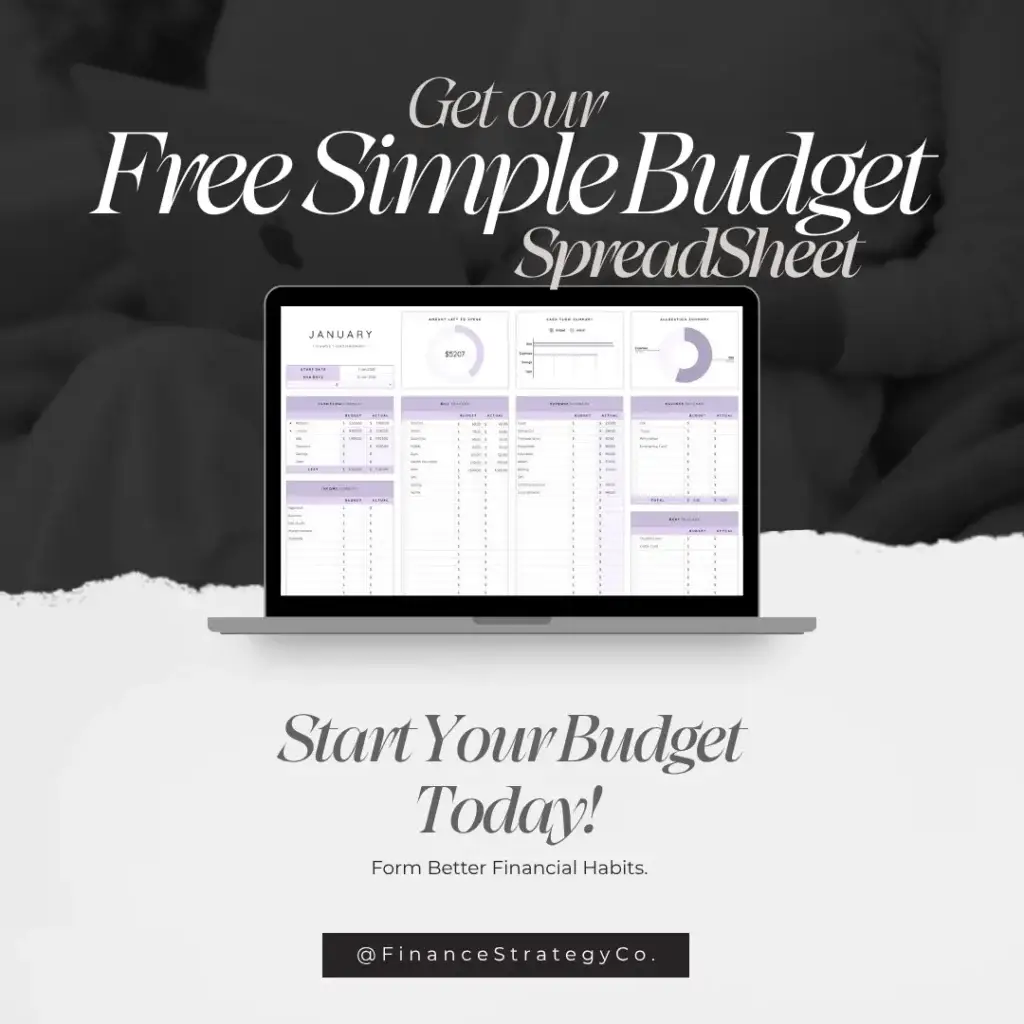
Finance Strategy Co. creates thoughtfully designed financial tools to help you organise your money, plan ahead, track your progress and build a financial system that fits your life.
Money management, elevated.