
Saving gives you security. Building wealth gives you options.
We often use the words saving and wealth building as though they mean the same thing.
They don’t.
Saving money and building wealth are both important parts of a strong financial strategy—but they serve different purposes.
Your savings can give you a financial cushion.
Your investments and other assets can help you build long-term wealth.
Your financial system brings them together.
The goal isn’t to choose between saving and building wealth.
It’s knowing when—and how, to use each.
At Finance Strategy Co., we believe your money should have a purpose.
Some of it is there to protect you today.
Some is there to create opportunities tomorrow.
And some is there simply to help you enjoy the life you’re living now.
Money management, elevated, starts with knowing the difference.
What Is Saving?
Saving is the process of setting money aside for future use.
It’s usually money you expect to need relatively soon or money you’re keeping available for financial security.
You might save for:
An emergency fund
A holiday
A new car
Home improvements
Annual bills
A large purchase
Upcoming expenses
Short-term financial goals
Saving is generally about preserving money and keeping it accessible.
Saving creates financial breathing room.
What Is Building Wealth?
Building wealth is about gradually increasing your overall financial position by accumulating assets and managing liabilities over time.
This might involve:
Investing
Superannuation
Property
Business ownership
Reducing debt
Building financial assets
Increasing your earning capacity
The aim is to create a financial foundation that can grow over the long term.
Wealth building is about creating future financial capacity.
Saving vs Building Wealth
The easiest way to understand the difference is to look at the purpose.
| Saving | Building Wealth |
|---|---|
| Protects money | Grows financial assets |
| Often short to medium term | Primarily long term |
| Focuses on accessibility | Focuses on growth |
| Creates financial security | Creates financial opportunity |
| Often involves cash | Can involve investments and other assets |
| Helps fund upcoming goals | Helps build future financial independence |
Neither is better.
They’re simply designed to do different jobs.
Saving Is About Security
Imagine an unexpected expense appears.
Your car needs repairs.
Your washing machine breaks.
You receive an unexpected medical or household expense.
Your income temporarily changes.
Without savings, you may need to rely on credit or borrow money.
With an emergency fund, you have a buffer.
That’s the power of saving.
It gives you room to respond.
Saving can therefore create something that isn’t easily measured on a spreadsheet:
Peace of mind.
Wealth Building Is About Growth
Now imagine you’re thinking ten, twenty or thirty years ahead.
You don’t simply want money sitting in an account.
You want to build assets that may grow over time.
This is where wealth building comes into the picture.
Depending on your circumstances, this could involve investments such as:
Shares
Exchange-traded funds
Managed funds
Property
Superannuation
Business interests
Different assets have different risks, potential returns and timeframes.
Wealth building requires a longer-term mindset.
The First Mistake: Thinking You Have to Choose
You don’t.
You can save and build wealth at the same time.
In fact, a strong financial strategy often includes both.
Think of it like this:
SAVING
Protects your present.
WEALTH BUILDING
Builds your future.
INTENTIONAL SPENDING
Allows you to enjoy your life along the way.
A balanced financial system gives each part of your money a purpose.
The Finance Strategy Method™
This is where the Finance Strategy Method™ comes into play:
KNOW → ORGANISE → PLAN → BUILD → THRIVE
Your financial journey begins with knowing where you stand.
Then you organise your money.
Then you create a plan.
Then you build towards your future.
And ultimately, you create the financial freedom to thrive.
Saving belongs in the foundation.
Wealth building belongs in the future.
Your strategy connects the two.
01 - Build Your Financial Foundation
Before focusing heavily on long-term wealth building, consider whether your financial foundation is strong.
Start by understanding:
Your income
Your expenses
Your debts
Your savings
Your financial commitments
Your emergency fund
This is the KNOW stage.
You can’t build confidently if you don’t know what you’re building from.
02 - Create an Emergency Fund
An emergency fund is one of the clearest examples of saving.
Its purpose isn’t to generate impressive returns.
Its purpose is to be available when you need it.
Your emergency fund can help cover unexpected costs such as:
Urgent repairs
Unexpected bills
Temporary income disruption
Essential household expenses
The appropriate amount will vary depending on your circumstances.
The goal is resilience.
03 - Create Short-Term Savings Goals
Not every financial goal needs to be an investment.
Some goals simply require you to save.
Perhaps you’re planning:
A holiday.
A wedding.
A new car.
A home renovation.
Annual insurance.
Christmas spending.
School expenses.
A major purchase.
These can be perfect candidates for dedicated savings.
Give your short-term goals their own place in your financial system.
04 - Separate Savings From Investments
One of the easiest ways to create clarity is to distinguish between money you’re saving and money you’re investing.
Savings
Money you may need relatively soon.
Investments
Money you’re generally setting aside for longer-term growth and that can fluctuate in value.
Keeping these purposes separate can help you avoid investing money you may need in the near future.
Your timeframe matters.
05 - Understand Your Time Horizon
Ask:
“When will I need this money?”
If the answer is:
Next month
Next year
Within a few years
You may be thinking primarily about saving and capital preservation.
If the answer is:
10 years
20 years
30 years
You may have more capacity to consider long-term investments, depending on your circumstances and risk tolerance.
Time changes the strategy.
06 - Understand Risk
This is where saving and investing differ significantly.
Cash savings generally provide accessibility and stability, although inflation can reduce purchasing power over time.
Investments can potentially provide greater long-term growth, but their values can rise and fall.
You could experience:
Market volatility
Temporary losses
Investment risk
Changes in returns
That’s why your investment strategy should consider:
Your goals
Timeframe
Risk tolerance
Financial circumstances
Higher potential returns generally come with greater risk.
07 - Don't Invest Your Emergency Fund
Your emergency fund has a different job.
It’s there for unexpected circumstances.
You generally don’t want to depend on an investment portfolio for an emergency because investment values can fall at exactly the wrong time.
Your financial foundation should be accessible.
Your long-term investments can then focus on long-term objectives.
08 - Build Your Wealth Once Your Foundation Is Strong
Once you’ve established an appropriate financial buffer and have a strategy for managing your debts and cash flow, you can focus more deliberately on wealth building.
Depending on your circumstances, this could involve:
Regular investment contributions
Superannuation contributions
Property
Business ownership
Debt reduction
Growing your income
Wealth building is a process.
It doesn’t need to happen all at once.
Saving Doesn't Always Build Wealth
This is an important distinction.
Having $20,000 in a savings account means you have $20,000 in an asset.
But if that money remains in cash for decades, inflation can reduce its purchasing power over time.
For example, if prices rise while your money doesn’t grow at a comparable rate, the amount of goods and services your money can purchase may decline.
This is one reason long-term wealth strategies often include investments.
Saving protects your money.
Investing can give it an opportunity to grow.
But Investing Isn't Always Better
It would be a mistake to interpret this as:
“I should invest everything.”
That’s not the point.
If you’re saving for a holiday next year, investing that money may expose you to unnecessary market risk.
If you need an emergency fund, accessibility matters.
If you’re saving for a major purchase in the near future, preserving the money may be more important than pursuing higher potential returns.
The right strategy depends on the job your money needs to do.
Think of Your Money in Buckets
A simple way to understand this is to divide your money into three broad purposes.
01 – TODAY
Money for everyday living.
Bills
Groceries
Transport
Lifestyle
02 – SECURITY
Money for protection and short-term goals.
Emergency fund
Upcoming expenses
Sinking funds
Short-term savings
03 – TOMORROW
Money for long-term growth.
Investments
Superannuation
Long-term wealth
Financial independence
Every dollar doesn’t need the same strategy.
The Role of Your Budget
Your budget connects your income to these different priorities.
Imagine your monthly income arrives.
Instead of thinking:
“What can I spend?”
You begin thinking:
“What job does this money need to do?”
Perhaps some goes towards:
Living expenses
Savings
Debt reduction
Investments
Lifestyle
Future goals
This is what makes budgeting more strategic.
You’re not simply restricting spending.
You’re allocating resources.
Saving Can Become a Habit
Saving isn’t only about the amount.
It’s about creating a habit.
Perhaps you start with:
$25 a week.
Then:
$50 a week.
Then:
$100 a week.
As your circumstances change, your savings strategy can change too.
The habit can become more valuable than the initial amount.
It teaches you to consistently direct money towards your future.
Wealth Building Can Become a System
The same principle applies to wealth.
You don’t necessarily need to make one enormous investment.
Instead, you can create a system.
For example:
PAYDAY
Income arrives.
↓
ORGANISE
Bills and essentials are funded.
↓
SAVE
Your savings contribution occurs.
↓
INVEST
Your long-term contribution occurs.
↓
SPEND
You enjoy the money remaining for your lifestyle.
A system removes some of the emotion from financial decisions.
What Comes First?
For many people, a sensible progression might look like:
1. Understand your finances.
Know your numbers.
2. Create a sustainable budget.
Make sure your cash flow works.
3. Build an emergency buffer.
Create financial breathing room.
4. Manage expensive debt.
Reduce financial obstacles.
5. Save for short-term goals.
Prepare for known expenses.
6. Build long-term assets.
Begin or strengthen your wealth-building strategy.
7. Review regularly.
Adjust as your circumstances change.
This isn’t a universal formula.
Your circumstances may require a different order.
Think of it as a framework, not a rulebook.
What About Debt?
Debt sits somewhere between saving and wealth building.
Some debt can help you acquire an asset.
Other debt can significantly reduce your ability to build wealth.
Consider the difference between:
$10,000 sitting in savings
and
$10,000 of high-cost consumer debt
Your overall financial position is affected by both.
This is why net worth matters.
Assets − Liabilities = Net Worth
Building wealth isn’t only about accumulating assets.
It’s also about managing liabilities.
Your Net Worth Tells the Bigger Story
Saving increases your assets.
Reducing debt decreases your liabilities.
Investing can potentially grow your assets.
Together, these actions can improve your net worth.
Imagine:
You increase your savings.
Your investment portfolio grows.
Your mortgage balance falls.
Your credit card debt disappears.
Your overall financial position strengthens.
That’s wealth building in action.
Saving for Today vs Building for Tomorrow
Let’s make it simple.
SAVING
“I need this money available.”
INVESTING
“I want this money to potentially grow over time.”
WEALTH BUILDING
“I want to create a stronger financial future.”
These ideas overlap, but they aren’t identical.
Knowing the difference allows you to make more intentional decisions.
How Much Should You Save?
There isn’t one perfect percentage for everyone.
Your ideal savings rate depends on:
Income
Expenses
Debt
Family circumstances
Financial goals
Timeframe
Lifestyle
Instead of asking:
“What percentage should everyone save?”
Ask:
“What amount can I consistently save without making my financial system unsustainable?”
Consistency matters.
How Much Should You Invest?
Again, there isn’t a universal number.
Your investment contribution should reflect your:
Financial position
Goals
Risk tolerance
Time horizon
Existing assets
Other commitments
If you’re unsure what approach is appropriate, consider seeking advice from a qualified financial professional.
Your investment strategy should be personal.
Don't Let Saving Become Hoarding
Saving can become counterproductive when fear prevents you from ever using your money.
You don’t need to save every dollar.
You don’t need to feel guilty about spending.
And you don’t need to postpone your entire life until some future financial milestone.
Money has a purpose today, too.
Your strategy should make room for:
Experiences
Relationships
Joy
Rest
Lifestyle
Building wealth shouldn’t mean forgetting to live.
Don't Let Investing Become Obsession
The opposite can happen too.
Someone becomes focused entirely on investment growth.
Every market movement becomes emotionally important.
Every purchase feels like a missed investment opportunity.
Every dollar spent creates guilt.
That’s not financial freedom.
Your investments are a tool.
Your money should support your life, not control it.
The Balance Between Security and Growth
Think about your financial life as a balance.
TOO MUCH CASH
You may miss opportunities for long-term growth.
TOO MUCH INVESTMENT RISK
You may not have enough accessible money when you need it.
TOO MUCH SPENDING
You may struggle to build financial security.
TOO MUCH RESTRICTION
You may create a lifestyle that doesn’t feel sustainable.
The goal is balance.
Not perfection.
Your Financial Strategy Should Have Three Horizons
A useful way to think about your money is through three timeframes.
NOW
What do you need to live well today?
NEXT
What financial goals are coming within the next few years?
LATER
What kind of wealth and freedom do you want to create over the long term?
Your financial system should make room for all three.
Because your future matters, but so does your present.
The Luxury of Financial Flexibility
True financial luxury isn’t necessarily about spending more.
It can be having the ability to choose.
To take time off.
To handle an unexpected expense.
To travel.
To change careers.
To start a business.
To support someone you love.
To say no to something that isn’t right for you.
Financial flexibility is a form of wealth.
And both saving and wealth building can contribute to it.
A Simple Example
Imagine you have an extra $500 available this month.
You could spend all of it.
You could save all of it.
Or you could create a strategy.
Perhaps:
$200 → short-term savings
$150 → long-term investing
$100 → debt reduction
$50 → lifestyle
The exact numbers aren’t important.
The principle is.
Your money can serve multiple purposes.
Build Wealth Without Losing Your Lifestyle
A common fear is that building wealth means becoming extremely frugal.
It doesn’t have to.
Instead, create intentional spending priorities.
Spend more freely on what genuinely matters.
Spend less on what doesn’t.
Save for upcoming goals.
Invest for your future.
You can enjoy your money and build wealth.
Those aren’t opposing ideas.
Your Wealth Journey Starts With Clarity
You don’t need to know exactly what your net worth will be in twenty years.
You don’t need to predict the market.
You don’t need to have every financial decision mapped out.
Start by asking:
What do I need to protect?
What am I saving for?
What am I building?
What kind of life do I want my money to support?
Those answers will begin to shape your strategy.
The Finance Strategy Method™
Let’s bring it back to the framework.
KNOW
Understand your income, expenses, assets, debts and net worth.
ORGANISE
Give your money different jobs.
PLAN
Create goals for today, tomorrow and the future.
BUILD
Save intentionally and build long-term assets.
THRIVE
Use your financial position to create greater freedom and choice.
KNOW → ORGANISE → PLAN → BUILD → THRIVE
This is the difference between simply managing money and creating a personal financial strategy.
Five Questions to Ask Yourself
Take a moment to consider:
01 – What am I currently saving for?
02 – Do I have enough financial breathing room?
03 – What long-term assets am I building?
04 – Is my money aligned with my financial vision?
05 – What is one thing I could improve this month?
You don’t need to answer everything immediately.
Start with one.
Saving Builds the Foundation. Wealth Building Builds the Future.
Saving and wealth building aren’t competing strategies.
They’re two parts of a bigger financial picture.
Saving can give you security.
Investing can create opportunities for long-term growth.
Debt reduction can strengthen your financial position.
Intentional spending allows you to enjoy your life along the way.
Together, they create a financial system that supports both your present and your future.
The Goal Isn't Just More Money
This is perhaps the most important idea.
You aren’t building wealth simply to see a larger number on a screen.
You’re building it for what that money can eventually make possible.
More choice.
More flexibility.
More security.
More freedom.
More opportunity.
That’s what makes wealth meaningful.
Your Money. Your Strategy. Your Future.
You don’t have to choose between enjoying your money today and building a better financial future.
You can create a strategy that allows you to do both.
Save for what matters now.
Build assets for what matters later.
Spend intentionally.
Reduce financial obstacles.
And keep your bigger vision in sight.
Because your money should do more than sit in an account.
It should support the life you’re creating.
KNOW → ORGANISE → PLAN → BUILD → THRIVE
Know where you stand.
Organise your money.
Plan for what matters.
Build your financial future.
And create the freedom to thrive.
That’s the Finance Strategy Method™.
And understanding the difference between saving and building wealth is an important step towards creating your own financial strategy.
Ready to Build a More Intentional Financial Life?
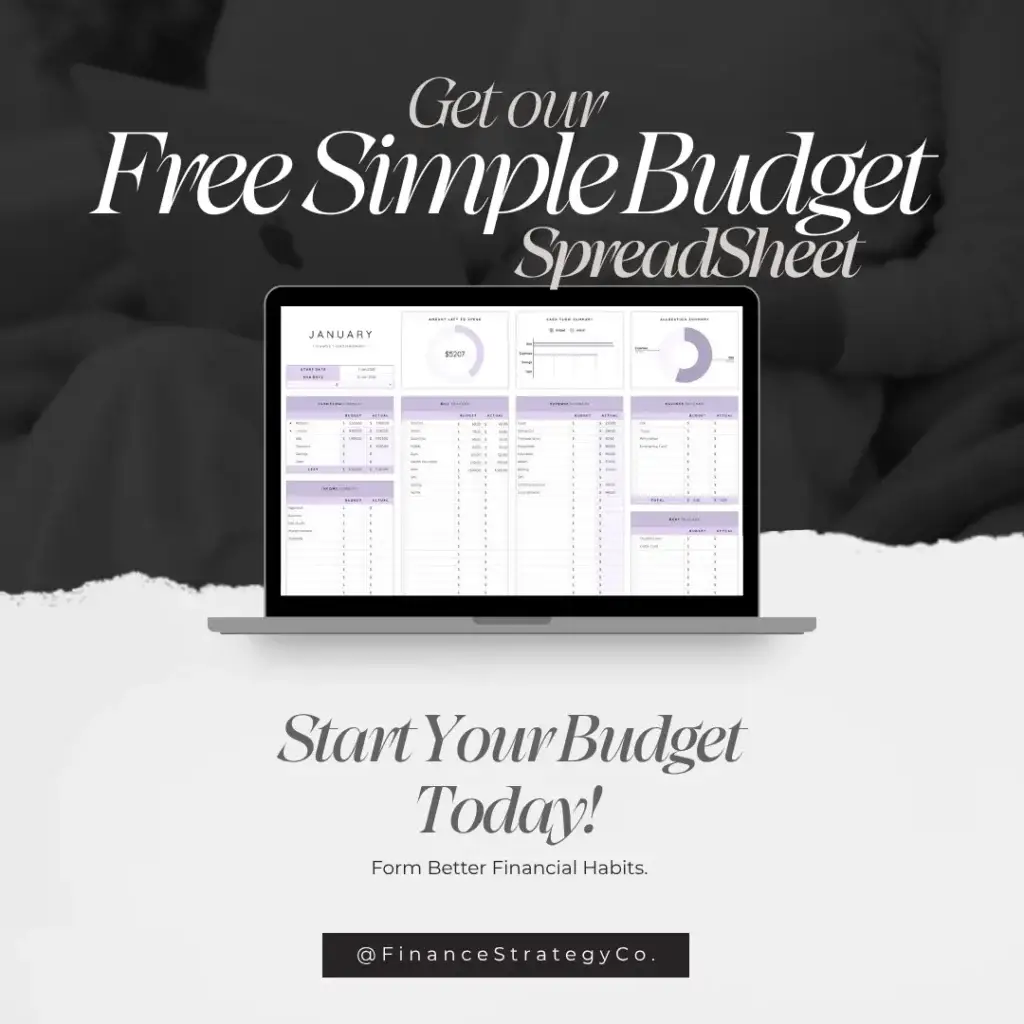
Finance Strategy Co. creates thoughtfully designed financial tools to help you organise your money, plan your goals, track your progress and build a financial strategy around the life you actually want.
Money management, elevated.